So, austerity is not working (big surprise) and my earlier plan for a Greek exit from the Euro is also now unworkable. The reason is that I think it is now impossible for the Greek government to get a hold of enough gold to make the plan workable. This was in fact already somewhat dubious before, but now it definitely isn't possible.
However there is still time to exit the Euro without consigning the Greek economy to the metaphorical basket. Unfortunately in this case the solution is only partially free market. I'm sorry, Greeks, it's the best I could think of.
What many people expect must ultimately happen is that Greece must create its own currency and replace all Euros in Greece with this new currency. This is a terrible plan (and yes, I know the alternatives are worse) because inevitably it will result in bank runs, people having their savings partially wiped out or, if hyperinflaion results, which is extremely likely, all of their savings.
My solution is a partial default. Tada.
It's obvious to everyone that this is what must happen, the only question is how. I believe my solution can provide bond holders with some confidence, protects the Greek people's savings, restores Greece's currency sovereignty and gives the lowest chance of hyperinflation. It also doesn't require any bank holidays
Brief outline:
The purpose of stage 1 is to prepare the world and Greece for the changes.
1. a) Announce debt repudiation. Redenominate all outstanding bonds in new Drachma currency at 1:1 Euro.
1. b) Announce low tax liability for transactions or income involving new Drachma.
1. c) Establish new Drachma as sovereign fiat currency receivable in taxes.
1. d) Announce no additional bond issuance by Greek government.
The purpose of stage two is to make the necessary changes to bring about a prosperous Greece.
2. a) Pay off bonds when due with newly printed Drachma.
2. b) Establish limiting of Drachma supply (to ultimate ceiling of total Drachma bond liabilities) to prevent hyperinflation.
2. c) Rapidly but smoothly reduce governent spending to near 0.
The purpose of stage three is to prevent the same from occurring ever again.
3. a) End fractional reserve banking and eliminate most legislation.
3. b) Create a new constitution.
3. c) Establish citizenry as the first line of policing and defence.
The first stage of this plan is to hit the bond holders with the default. Announce that all outstanding Greek bonds will be redenominated in the new currency, which I will call Drachma. This will not be popular, but it is necessary and bond holders will prefer it to alternatives, because they will be the first reipients of the new currency.
A parallel announcement will be made in Greece that the new currency will attract a consumption tax of say 10% and no other taxes of any kind. This is in order to drive demand for the Drachma over the Euro in Greece itself. If the tax for Euros is high and for Drachmas is low, people will start to prefer it. This is how the Drachma is monetised in Greece. At this point no Drachma are in the possession of any Greek. The Euro and Drachma will be parallel currencies until the Euro is effectively demonetised. Both will be acceptable for tax liabilities.
Stage two is to print new Drachma to pay off the bonds denominated in Drachma. The new money will be fully sovereign currency - in other words, no bonds will be required to expand the money supply. The size of the money supply will be determined by the Greek government, but an excellent practice would be to only print all money necessary to pay off the existing bonds, and then only print such money as is needed to replace worn out currency. The money supply will be constant. There will be no need for a central bank as such, only a government printer replacing worn out notes and a mint to coin the lower denominations. Constant money supply will make it an exceedingly safe currency and increase its trust and money value in the eyes of trading partners and the Greek people themselves. It makes hyperinflation an extremely remote scenario.
Fractional reserve banking would end.
The era of Greek government bonds would have to end - only a balanced budget would be possible going forward. This will be an economic shock, for sure, but people will be heartened by the low taxes in their near future. Investors might well find Greece an attractive place to do business if they are confident that business could be conducted in a currency that attracted minimal taxes. This would be a big boost to confidence in Greece itself and prevent the depression from spiralling too far. Once Drachma started to circulate back to the government it would be time to redenominate certain avenues of government spending in Drachma. What is clear is that with Drachma taxes so low Greek government spending will also need to decrease drastically. The shock of this, as stated before, will be partially offset by dramatic increases in investment funds flooding the newly liberalised Greek economy and low priced labour. Even so, great care would be taken to make sure that people relying on the State for their livelihood are not suddenly dumped. Pensioners and the old are particularly vulnerable, so might be worthy recipients of newly printed Drachma themselves. They might be considered a secondary vehicle for the monetisation of the Drachma, however this is not really necessary. The 10% consumption tax will soon provide adequate funds to give state dependents a living income if they have no other sources, however entitlements will have to be the same for all recipients and anyone with an amount of Euro savings would not be eligible. All previously contracted pension obligations would have to be reneged on. All government employees would have to gradually be given the sack and join the real economy which hopefully will begin to boom because of the influx of investment.
Two major exceptions are police and military. In the mean time the police and military would be responsible for maintaining law and order and preventing foreign invasion, respectively. To aid law enforcement all Greek adults would be encouraged to buy and carry firearms that may be used to deter unauthorised access to one's property. However this will not be a free for all in murder because the police would still treat any death as a potential murder case. Citizens should be encouraged to use non-lethal force except in cases of imminent threat to life. The number of police and military personnel could thus be greatly reduced, leaving the state's main spending to the old who cannot adapt to the new situation, and the small number of law enforcement and judicial officials. It is clear that only the most basic laws could be handled under this reduced judicial system. No fraud, no theft, no rape, no murder would pretty much be the scope. In such severe times all other regulations are an unacceptable burden. What remains of the government should focus on creating a new constitution that enumerates the constant money supply condition, a common law framework, and otherwise establishes the Greek people as the master of their government, not the other way around.
In the long run, whatever happens Greece will eventually recover. The purpose of this plan is to make that transition as fast and painless as possible - for Greece and the rest of Europe. It requires a radical rollback of the Greek state and a radical plan for monetising a new currency, but when the situation is unique the solutions must be also. I only hope that whatever happens is as kind or kinder to all parties than my proposal.
This plan may begin implemetation at any time, under almost any conditions as long as the government sitll exists and has some clout. It goes without saying, however, that sooner is better. Between the beginning of stage one and the end of the whole process would be about two years, so time is of the essence. I greatly fear that no such plan will be used and the Greek people and other Europeans of modest means will continue to suffer under the heavy yoke of poor growth and high taxes. If that happens things could become violent, and no one wants that.
Showing posts with label economics. Show all posts
Showing posts with label economics. Show all posts
Monday, 21 May 2012

Thursday, 10 May 2012
A fresh look at Austrian business cycle theory
I recently read a very interesting critique of the Austrian business cycle theory (ABC), and I just couldn't resist adding a few of my thoughts. Here follows my comment on the piece.
All of this suggests what I have been thinking about for a while: the best monetary policy is one where the central bank does not alter the money supply at all. I really need to do some analysis to find out if this theory is borne out by the facts but that is for another time. Look for future posts on this topic.
EDIT: I realised after this that the central bank can continue to inflate even at high levels without this causing hyperinflation (which as I define it is not to be thought of as a threshold level of price rises) because the economy can adjust to permanent money supply increases. It all depends on the psychology of the people and whether they are willing to accept the situation. If they do accept it then through the general ignorance of the effects of inflation real wealth will be transferred to those otherwise unprofitable enterprises.
1,2,3) If a lot of capital goods turned out to be in the wrong use at the same time then a large investment in labour would be required to convert them. Capital conversion is thus a natural part of the economy but would spike at certain times - namely some time during a recession. The same applies to labour itself because retraining takes time of course, and when a person studies he is investing intellectually in that career path.
4,5) Any unnatural change in the money supply will cause a shock, it is just that those shocks are of a different kind. Gradually falling prices are no problem if the money supply is not contracting in a sudden unnatural way. Austrians, I think rightly, blame the fact that such a deflation shock can occur at all on the prior inflation. Once the money supply has been unnaturally (through fiat inflation, FRB expansion, take your pick) increased price stability becomes impossible, because as that additional money filters through the economy and increases the price level the only way to put a halt to that price increase is to actually reduce the money supply. The severity of this will be decided by what level of inflation is considered acceptable. Thus I think that it is the central bank's desire to prevent the price inflation that causes much of the "downside" problem. It would be a much better policy to refuse to change the supply in any way and allow prices to stabilise at a higher level.
6,7,8) I think it is reasonable to say that Austrians discount risk in the interest rate issue. The question then becomes, is it that lower interest rates will decrease savings because of poor returns or increase them because of lower perceived risk? I think this is at the core of what causes the business cycle, because low interest rates will cause low yield investments to become more populous while at the saver end the average man will save less because the perceived risk in a bank is usually close to 0, and thus the interest rate is very much a supply/demand. Personally I think that at very low interest rates (say, less than 3%) the savings rate is inelastic because those savings are prudential rather than an investment.
So if we assume that time preference is the wrong way to look at it and we instead consider risk perception, we need to understand why perception changes suddenly. I believe that the injection of cash into the investment sector will gradually cause the prices of capital goods to rise and at some tipping point it will become evident that some enterprises will not be profitable under the current price levels and expected future prices (for capital goods). These higher prices will thus conceivably cause a crash in the demand for capital goods as the contageon spreads. The demand crash causes unemployment from those unprofitable companies, causing a demand crash in the consumer goods sector as well, further exascerbating the unemployment problems.
As a result of these demand crashes only the highly profitable producer companies will be able to keep trading. From their perspective it is better if the money supply remains constant because then the price inflation will allow them to pay off their creditors through higher numerical revenue despite decreased sales. If the central bank elects to focus on inflation and raises interest rates these companies will face reduced revenue and higher interest rates, likely making many of them insolvent as well. I believe this is a very plausible explanation for the Great Depression, since we know deflation occurred. In a sense the motivations for deflation are immaterial - it will cause a bust proportionate to the deflation. The magnitude of the impact of the previous inflation is then a function of how far deflation is allowed to continue - if it goes to the money supply before the boom then it will be as mild as the boom, if allowed or forced all the way down to the monetary base then you could have a truly catastrophic contraction unless the boom started when the money supply was already at the monetary base.
The Austrians do have the cause of producer goods price rises correct, I believe: that low interest rates cause real savings to be lower than real investment, thereby eventually causing increased competition between consumers and producers for raw materials.
So to summarise: deflation is bad because it causes naturally profitable enterprises to go bust, inflation is bad because it causes naturally unprofitable enterprises to be started. There's a pleasing symmetry there, isn't there?
10,11,12) I agree with most of what you said here. Under my construction the idea of a malinvestment is in a sense not there. The investments are all profitable when investment is high and prices are still low. So it's not that the entrepreneurs make a mistake at the time given the conditions, it's that later price increases are unforseen and reveal those investments as unprofitable. The difference, in real terms, between a profitable and unprofitable enterprise is that the former uses fewer real goods than are given up by people when they save, and the latter uses more. The problem with a boom is that it reduces the real resources available to those enterprises on the margin and makes many otherwise profitable ventures fail when the bust comes.
Any way you cut it some companies will have to fail. There are only three options: Deflation, which destroys profitable companies; constant money, which I believe is the cure; and inflation which, in order to prevent the failure of those companies that used real resources not "saved" by consumers would have to constantly increase until the result was hyperinflation. That's the only way to get the necessary "forced saving" and hyperinflation will be inevitable as people realise their money is losing value, since by definition they will be forced to give up more real goods than they actually want to.
All of this suggests what I have been thinking about for a while: the best monetary policy is one where the central bank does not alter the money supply at all. I really need to do some analysis to find out if this theory is borne out by the facts but that is for another time. Look for future posts on this topic.
EDIT: I realised after this that the central bank can continue to inflate even at high levels without this causing hyperinflation (which as I define it is not to be thought of as a threshold level of price rises) because the economy can adjust to permanent money supply increases. It all depends on the psychology of the people and whether they are willing to accept the situation. If they do accept it then through the general ignorance of the effects of inflation real wealth will be transferred to those otherwise unprofitable enterprises.
Wednesday, 18 April 2012
Reasons why you should never buy a government bond
If there's one financial asset that should really be treated like radioactive ebola virus, it's the government bond. In the past this was not necessarily true, because way back when gold and silver were money and when the government's debts fell due it had to find the money somewhere to repay it. It had to increase taxes. This might not sound like such a fantastic thing, and you right, it's not - really all governments should run balanced budgets no matter what, but at least back then people knew what was going to happen. Of course such tax hikes in the wake of government borrowing were pretty unpopular so all monarchs were always looking for a way around that and the most effective instrument was coin clipping. Governments would reduce the precious metal content of their coins but remint them at the old valuation. When this became really popular after a while you end up with something like the late Roman Denarius with a precious metal content of 0-1%.
All this is to underline why government debt is always a bad investment. In recent times the debt of stable, high performing economies like the US, Switzerland and Germany has come under such high demand that in Switzerland the yield is now negative. In other words, the price of the bonds themselves are now so high that investors are certain to lose money, even after you consider the interest the bonds are going to pay. They are willing to lose the money because they are so afraid of any other inverstment crashing and they want something that is certain to repay their money. All of these investors are going to lose their money, or if not them, then whoever ends up with the equivalent of those bonds down the track. This is certain. Even the ever prudent Swiss or the mighty Germans will eventually end up in the same sort of tight spot Greece, the US and all the rest. Let me explain why.
First we need to examine the purpose of government debts. When a private company goes into debt it usually uses that money to invest in plant, land, resources, anything they need to grow the business and generate the profits that are going to repay the loan plus interest and leave them with plenty of new cash left over. When the government goes into debt it never does it with the intention of spending on things that will eventually repay the debt. This was originally the theory - the government would borrow from its citizens, do some large construction project like a road or a dam or whatever it might be, and as a result of this new infrastructure the economy would be more productive and the tax take would increase and allow the repayment of the original debts. Precious though this theory was to satisfy the general populace that they wouldn't suffer a burden of extra taxes later to make up for it this is not how it has ever, to my knowledge, worked out. The investment was always supposed to pay itself back in taxes and even if it didn't, the bond holders had no fear because if the project turned out to be a dud they would get their money back anyway because the government could always tax the rest of the people more to make up the shortfall. However this lovely theory has never been a reality. The reasons are multiple but the chief reasons are a) if the government's idea for an investment was profitable private investors would be doing it already and b) if - and I stress, if - the government's plan actually did make the economy more productive and did increase the tax take, none of that tax was ever earmarked for the purposes of repaying the debt. It was always more tempting to spend that money straight away and worry about the bondholders when the time came. And what typically happens when it actually does come time to worry about the bondholders? Naturally the government does not actually have the money, so instead of risking the unpopularity of forcing the populace to actually pay for the stuff the goverment had bought on their behalf, it simply sells new bonds to pay off the old bonds.
Are you seeing the problem now? You see now why those bondholders were stupid to buy the bonds at all? The government's incentives always lie towards repaying old debts with new debts. That's why nearly all western governments have had a sustained increase in debt. No one ever stopped to think about the fact that these were loans and that eventually people might ask for their money back and lose faith in the government to such a degree that they would not be willing to give up any more. Everyone knows the US government is never ever going to repay their bonds, and even so investors are still giving it up for new bonds in the certain knowledge that the money ultimately won't be repaid. They simply expect that at some future date they'll be able to find another sucker to sell it to before the bottom falls out, or that the bond will fall due and they won't be trapped into buying back into America's pyramid scheme right before it all goes west. The only reason, in other words, that the bonds have any value at all right now is because the investors expect to be able to sell them or get paid back by the US government before it has to resort to devaluing the Dollar, which, by the way, it has already been doing heavily.
Greece is substantially different from the US. In the US if they really wanted to give those bond holders back their dollars they could always print some up and give everyone their full amount. Of course that would result in instant hyperinflation the minute the investors started to try to buy real stuff with that money, but their bank accounts would at least have the right number in them. In Greece they're on the Euro standard which is one of the reasons for their woes. They can't repay the bonds they've issued because the only place for those euros to come from is taxes and the only way the economy could ever sustain such a tax take is if they were brilliant exporters to the rest of the Eurozone or, failing that, to anywhere else in the world. Needless to say, they are not. As a result of this Greek bond holders (not necessarily Greeks, people holding their bonds) have already had to take a "voluntary haircut" of 74%. That means that every single person who owned a Greek bond just before the bottom fell out has lost 74% of his money and that's despite the bailouts. Spanish, Portuguese, Italian, and other bond holders are on the same road, which is why recently they've started to edge away from those bonds, resulting in a spike in long-term bond yields:
 So, to recap: you should never buy a bond because no government will ever pay it back in the long term. Even if you get your money back it's at the expense of some other sucker down the line, and even if he gets his money back in nominal terms its value will be so low he'll wish he hadn't. The eventual crisis is certain to come and when it does the economy of that country is going to tank. Do you want to be partly responsible for making that government's spending possible? Do you want to wear even a millionth part of the blame for lowering the interest rate on those bonds, which kept the state spending and made the eventual collapse worse? State issued bonds are simply a deferred stealth tax - a tax that deludes people into thinking it's an investment and produces a massive crisis when people snap out of it and realise they'll never see their money again. Now that you know, if you have a conscience or any compassion for your fellow man, don't buy a government bond. Not a single one. Not ever.
All this is to underline why government debt is always a bad investment. In recent times the debt of stable, high performing economies like the US, Switzerland and Germany has come under such high demand that in Switzerland the yield is now negative. In other words, the price of the bonds themselves are now so high that investors are certain to lose money, even after you consider the interest the bonds are going to pay. They are willing to lose the money because they are so afraid of any other inverstment crashing and they want something that is certain to repay their money. All of these investors are going to lose their money, or if not them, then whoever ends up with the equivalent of those bonds down the track. This is certain. Even the ever prudent Swiss or the mighty Germans will eventually end up in the same sort of tight spot Greece, the US and all the rest. Let me explain why.
First we need to examine the purpose of government debts. When a private company goes into debt it usually uses that money to invest in plant, land, resources, anything they need to grow the business and generate the profits that are going to repay the loan plus interest and leave them with plenty of new cash left over. When the government goes into debt it never does it with the intention of spending on things that will eventually repay the debt. This was originally the theory - the government would borrow from its citizens, do some large construction project like a road or a dam or whatever it might be, and as a result of this new infrastructure the economy would be more productive and the tax take would increase and allow the repayment of the original debts. Precious though this theory was to satisfy the general populace that they wouldn't suffer a burden of extra taxes later to make up for it this is not how it has ever, to my knowledge, worked out. The investment was always supposed to pay itself back in taxes and even if it didn't, the bond holders had no fear because if the project turned out to be a dud they would get their money back anyway because the government could always tax the rest of the people more to make up the shortfall. However this lovely theory has never been a reality. The reasons are multiple but the chief reasons are a) if the government's idea for an investment was profitable private investors would be doing it already and b) if - and I stress, if - the government's plan actually did make the economy more productive and did increase the tax take, none of that tax was ever earmarked for the purposes of repaying the debt. It was always more tempting to spend that money straight away and worry about the bondholders when the time came. And what typically happens when it actually does come time to worry about the bondholders? Naturally the government does not actually have the money, so instead of risking the unpopularity of forcing the populace to actually pay for the stuff the goverment had bought on their behalf, it simply sells new bonds to pay off the old bonds.
Are you seeing the problem now? You see now why those bondholders were stupid to buy the bonds at all? The government's incentives always lie towards repaying old debts with new debts. That's why nearly all western governments have had a sustained increase in debt. No one ever stopped to think about the fact that these were loans and that eventually people might ask for their money back and lose faith in the government to such a degree that they would not be willing to give up any more. Everyone knows the US government is never ever going to repay their bonds, and even so investors are still giving it up for new bonds in the certain knowledge that the money ultimately won't be repaid. They simply expect that at some future date they'll be able to find another sucker to sell it to before the bottom falls out, or that the bond will fall due and they won't be trapped into buying back into America's pyramid scheme right before it all goes west. The only reason, in other words, that the bonds have any value at all right now is because the investors expect to be able to sell them or get paid back by the US government before it has to resort to devaluing the Dollar, which, by the way, it has already been doing heavily.
Greece is substantially different from the US. In the US if they really wanted to give those bond holders back their dollars they could always print some up and give everyone their full amount. Of course that would result in instant hyperinflation the minute the investors started to try to buy real stuff with that money, but their bank accounts would at least have the right number in them. In Greece they're on the Euro standard which is one of the reasons for their woes. They can't repay the bonds they've issued because the only place for those euros to come from is taxes and the only way the economy could ever sustain such a tax take is if they were brilliant exporters to the rest of the Eurozone or, failing that, to anywhere else in the world. Needless to say, they are not. As a result of this Greek bond holders (not necessarily Greeks, people holding their bonds) have already had to take a "voluntary haircut" of 74%. That means that every single person who owned a Greek bond just before the bottom fell out has lost 74% of his money and that's despite the bailouts. Spanish, Portuguese, Italian, and other bond holders are on the same road, which is why recently they've started to edge away from those bonds, resulting in a spike in long-term bond yields:
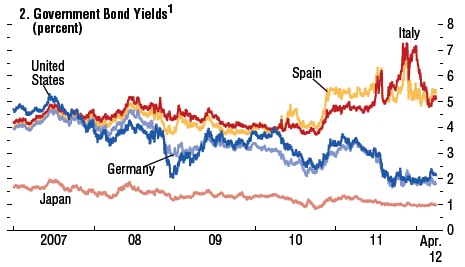 So, to recap: you should never buy a bond because no government will ever pay it back in the long term. Even if you get your money back it's at the expense of some other sucker down the line, and even if he gets his money back in nominal terms its value will be so low he'll wish he hadn't. The eventual crisis is certain to come and when it does the economy of that country is going to tank. Do you want to be partly responsible for making that government's spending possible? Do you want to wear even a millionth part of the blame for lowering the interest rate on those bonds, which kept the state spending and made the eventual collapse worse? State issued bonds are simply a deferred stealth tax - a tax that deludes people into thinking it's an investment and produces a massive crisis when people snap out of it and realise they'll never see their money again. Now that you know, if you have a conscience or any compassion for your fellow man, don't buy a government bond. Not a single one. Not ever.
Saturday, 14 April 2012
Economic fallacies abound at the UN
The recent United Nations High Level Meeting on Wellbeing and Happiness has shown how widespread certain economic fallacies are among the great and the good. Of course we knew this before, but it gives me a special chill every time some high level world leader opens his or her mouth and says something like:
First of all, one of the primary fallacies of modern day environmental movements is that there are limits to the size of the economy. To understand why this is a fallacy, let's think a bit about what economic growth means in real terms. Typically it means that more stuff is being traded, or that the value of the stuff being traded increases. Less valuable resources are converted into more valuable ones using energy and human ingenuity. The limiting factors that control how much value is added are a) the amount of energy available for that process and b) how ingenious the process and product are. Energy is always finite, but there are no known limits to human ingenuity. We can always make what we're making more efficiently, and we can always find a way to make it more useful. Computers are an almost perfect example of this. They keep getting cheaper and more powerful, with no end in sight. Once we reach the limits of elemental semiconductors, we'll just move on to something even faster more efficient and just better in every way. What that is remains to be seen, but graphene, optical chips and quantum computing are all watchwords for the near-computing-future.
The same reasoning applies to all things. They can always be made more cheaply, of higher quality and greater utility. That fact means there are no currently known practical upper limits to the economy. And I very much doubt there ever will be. GDP for its own sake is stupid, but if the market is allowed to function, there are no limits to GDP, no limits to personal wealth.
We also cannot run out of natural resources. Every now and again you will hear the doom-mongers say that we only have 20 years left of silver or whatever. That's nonsense. They seem to miss the fundamental fact that after silver (for example) has been mined it doesn't actually disappear, it is made into goods. We therefore cannot "run out" of it - if we ever reach a point where all practically exploitable mines have been exhausted, we will just recycle the silver we've already mined into the most useful forms. The price system will take care of that automatically. This applies to all rare resources and yes, that includes oil, coal and the rest of the non renewable energy resources. We genuinely can "run out" of them but when we do we'll just make more any way we can from raw materials using some other form of energy. It's already been done.
The idea that the economy enslaves us is, again, a common fallacy. I stated in a previous entry on money that we are not serving Mammon but other people. The very division of labour that provides such bounty would allow someone to work only a few hours a week for all the food he needs. If that same person wanted to live off nature he would be forced to work constantly just to stay alive.
The GDP-led development model that compels boundless growth on a planet with limited resources no longer makes economic sense. Within its framework, there lies no solution to the economic, ecological, social and security crises that plague the world today and threaten to consume humanity.That was the Prime Minister of Bhutan, but lots of people feel the same way. GDP, unreliable measure that it is, tells us very little about what is actually happening in the economy. The raw aggregate tells us PQ (nominal GDP: the price level multiplied by total output) from which economists and statesticians attempt to extract Q (real output or "real GDP") which is supposed to measure how much stuff is being traded in the economy.
First of all, one of the primary fallacies of modern day environmental movements is that there are limits to the size of the economy. To understand why this is a fallacy, let's think a bit about what economic growth means in real terms. Typically it means that more stuff is being traded, or that the value of the stuff being traded increases. Less valuable resources are converted into more valuable ones using energy and human ingenuity. The limiting factors that control how much value is added are a) the amount of energy available for that process and b) how ingenious the process and product are. Energy is always finite, but there are no known limits to human ingenuity. We can always make what we're making more efficiently, and we can always find a way to make it more useful. Computers are an almost perfect example of this. They keep getting cheaper and more powerful, with no end in sight. Once we reach the limits of elemental semiconductors, we'll just move on to something even faster more efficient and just better in every way. What that is remains to be seen, but graphene, optical chips and quantum computing are all watchwords for the near-computing-future.
The same reasoning applies to all things. They can always be made more cheaply, of higher quality and greater utility. That fact means there are no currently known practical upper limits to the economy. And I very much doubt there ever will be. GDP for its own sake is stupid, but if the market is allowed to function, there are no limits to GDP, no limits to personal wealth.
We also cannot run out of natural resources. Every now and again you will hear the doom-mongers say that we only have 20 years left of silver or whatever. That's nonsense. They seem to miss the fundamental fact that after silver (for example) has been mined it doesn't actually disappear, it is made into goods. We therefore cannot "run out" of it - if we ever reach a point where all practically exploitable mines have been exhausted, we will just recycle the silver we've already mined into the most useful forms. The price system will take care of that automatically. This applies to all rare resources and yes, that includes oil, coal and the rest of the non renewable energy resources. We genuinely can "run out" of them but when we do we'll just make more any way we can from raw materials using some other form of energy. It's already been done.
We desperately need an economy that serves and nurtures the wellbeing of all sentient beings on earth and human happiness that comes from living life in harmony with the natural world, with our communities and with our inner selves. We need an economy that will serve humanity, not enslave it.If there's one sure way of making people poor, its denying them the market. Goods sold on the market are sold because they help people's wellbeing in some way. They help serve people. Whether that is a function of producing things or just being useful to people in itself, all things are sold because people want them, and people want them because they are useful. In economic parlance, they "give ease". The reason we do not live in harmony with the natural world, whatever that means, is because a) few naturally produced resources are useful in their totally natural form and b) if we did then most people would have to die, because farming is unnatural and the level of population the earth can sustain without agriculture is extremely low. Living in harmony with nature is living in slavery, because no matter how ingenious a plan it cannot be implemented without changing nature in some way. You cannot build a house without annexing some ground that could have been used by nature for plants. All of this is to say that humans are meant to be masters of nature, the Bible even says so. This does not mean that we may destroy it, of course, but we may certainly change it so that it better serves us. That's what we have been doing ever since we began to exist, and nothing will ever stop us doing it. Mastery of nature is what provides us with wellbeing in terms of medicine, easy labour, high food production, comfortable living and work spaces, pleasing entertainment. If you want to give that up and live like a savage again feel free, but don't complain if no one else does.
The idea that the economy enslaves us is, again, a common fallacy. I stated in a previous entry on money that we are not serving Mammon but other people. The very division of labour that provides such bounty would allow someone to work only a few hours a week for all the food he needs. If that same person wanted to live off nature he would be forced to work constantly just to stay alive.
Prime Minister Thinley concluded by reminding the gathering that “business as usual cannot go on and tinkering with the existing system will not do… we need a fundamental transformation”.A fundamental transformation. Well, yes I'd like to see free markets everywhere. That would be a great fundamental transformation. Time to get the State out of the way of commerce so that resources can be exploited more efficiently. I wonder what sort of fundamental transformation he has in mind, and whether it will be popularly demanded or simply imposed by force.
Saturday, 31 March 2012
There's that unicorn again ...
Last time I found something totally rediculous written by an MMT theorist I remarked on facebook: "Inflation is always and everywhere a monetary phenomenon." It is a result of an increase in fiat money supplies. Government deficits are inflationary, even if bonds are issued. The only just way for a fiat money system to exist is under constant money supply conditions - no growth or reduction in the money supply at all by anyone.
Tuesday, 20 March 2012
MMT or Money Matters noT
I'm really very sorry to inflict this on my readers but I simply have to talk a little bit about this MMT stuff. I was reading an article today on BillyBlog and part of it nearly made me cough out my own uvula.
It starts well:
So the money supply is determined by the interest rate, and the interest rate by the amount of bank reserves (rather, by the percentage change of those reserves), and the bank reserves are controlled by central bank ... so how is that not the central bank determining the money supply? Yeah it doesn't actually go, we need $5T this year, we'd better print it up, but it has every intention of changing the money supply when it changes interest rates, because it's targeting inflation, so why not call a spade a spade?
He also seems to assume that the amount of money in the economy is supposed to increase with GDP. This is one of the more pervasive myths of economics. The quantity theory of money says, broadly, that the money supply at one time t has some value x. It would have value x no matter what the total number of dollars actually was, since money's only function is to enable trade and it will serve that function whether a cent buys a paperclip or a nuclear power station. Decimalised currency can be divided into arbitrarily small units so we can always make change no matter what we buy. Bill seems to completely ignore that by assuming that the money supply should grow with the economy. In fact it does not have to, all that matters is how exactly it changes in size. If a market amount of labour is required to produce it then all is well. If the cost of producing it is way below its "value" in the economy, then the first spenders get by far the most benefit from its creation. The latter state is the current situation in every country on earth and is 90% of the reason we are in so much debt right now. Governments and banks create the money and they get the benefit.
Later he continues:
More than anything else the MMT school totally ignores the movement of real wealth in the economy, which is the whole point of the thing. Economics is not just about making the numbers work, it's about real people trading real things for real benefits. The MMT model places the central bank and the government firmly in control of the economy, and as such is really another form of statism, which all economic models are at some level apart from the laissez faire Austrian school. In a way it is the worst because it understands the full implications of state control of the money system. It encourages the state to use its power for good but never questions whether the state ought to have the power at all, which I believe with all my heart it should not.
We must bring back market money. It has been totally abandoned and we are blessed with the collapse of our economy as a result. We must bring back sound money, sane interest rates determined by the market, end fractional reserve banking forever, and abandon the idolatry of a government solution to every private problem.
It starts well:
The essential idea is that the “money supply” in an “entrepreneurial economy” is demand-determined – as the demand for credit expands so does the money supply.It goes on:
As credit is repaid the money supply shrinks. These flows are going on all the time and the stock measure we choose to call the money supply, say M3 (Currency plus bank current deposits of the private non-bank sector plus all other bank deposits from the private non-bank sector) is just an arbitrary reflection of the credit circuit.OK, no problem with that so far ...
So the supply of money is determined endogenously by the level of GDP ...Pardon my French but WHAT THE FUCK? MMT is constantly throwing up rubbish like this that just makes you think you've gone mad. He is arguing that the central bank does not determine the money supply, it is determined by the amount of credit lent out of banks. I actually have no beef with that as a statement of truth, I mean I hate it with a passion but it's still just as true. But the other real problem here is that he seems to be saying that the central bank does nothing that affects the money supply, which is plainly false and he must know it. The central bank determines interest rates for the entire economy, and thereby directly controls the amount of money that is lent out, since low interest rates will result in more lending (in the short term) and high interest rates less. The reason for that is that the interest rate it sets is fairly arbitrary, but whatever it is the economy can only support x number of dollars borrowed at some interest rate and it can support only fewer dollars lent out at a higher interest rate, since the only projects getting loans at the higher rate will be those that are forecast to provide a higher return, allowing the interest to be paid off. The actual number of dollars in bank reserves is irrelevant, only the interest rate those reserves produce is relevant.
So the money supply is determined by the interest rate, and the interest rate by the amount of bank reserves (rather, by the percentage change of those reserves), and the bank reserves are controlled by central bank ... so how is that not the central bank determining the money supply? Yeah it doesn't actually go, we need $5T this year, we'd better print it up, but it has every intention of changing the money supply when it changes interest rates, because it's targeting inflation, so why not call a spade a spade?
He also seems to assume that the amount of money in the economy is supposed to increase with GDP. This is one of the more pervasive myths of economics. The quantity theory of money says, broadly, that the money supply at one time t has some value x. It would have value x no matter what the total number of dollars actually was, since money's only function is to enable trade and it will serve that function whether a cent buys a paperclip or a nuclear power station. Decimalised currency can be divided into arbitrarily small units so we can always make change no matter what we buy. Bill seems to completely ignore that by assuming that the money supply should grow with the economy. In fact it does not have to, all that matters is how exactly it changes in size. If a market amount of labour is required to produce it then all is well. If the cost of producing it is way below its "value" in the economy, then the first spenders get by far the most benefit from its creation. The latter state is the current situation in every country on earth and is 90% of the reason we are in so much debt right now. Governments and banks create the money and they get the benefit.
Later he continues:
Again, no arguments there, but there is a little fly in the ointment called the interest rate. As I have argued previously, fewer people will be credit-worthy at a higher interest rate than at a lower one, so while banks are not technically reserve constrained they have to raise interest rates if their reserves are being persistently depleted, both in order to increase profits and to decrease the number of people making demands on their reserves. If they do not they will always have to borrow reserves and that is more expensive than having them in the form of demand deposits, their profits will fall relative to the other banks and they will be driven out of the market.To repeat, bank lending is not “reserve constrained”. Banks lend to any credit worthy customer they can find and then worry about their reserve positions afterwards. If they are short of reserves (their reserve accounts have to be in positive balance each day and in some countries central banks require certain ratios to be maintained) then they borrow from each other in the interbank market or, ultimately, they will borrow from the central bank.
More than anything else the MMT school totally ignores the movement of real wealth in the economy, which is the whole point of the thing. Economics is not just about making the numbers work, it's about real people trading real things for real benefits. The MMT model places the central bank and the government firmly in control of the economy, and as such is really another form of statism, which all economic models are at some level apart from the laissez faire Austrian school. In a way it is the worst because it understands the full implications of state control of the money system. It encourages the state to use its power for good but never questions whether the state ought to have the power at all, which I believe with all my heart it should not.
We must bring back market money. It has been totally abandoned and we are blessed with the collapse of our economy as a result. We must bring back sound money, sane interest rates determined by the market, end fractional reserve banking forever, and abandon the idolatry of a government solution to every private problem.
Thursday, 1 March 2012
STOP PRESS Scientist announces results of experiment without using a control group
A recent article in The Conversation has me wondering what Linda Weiss did to become a scientist. She argues that all economies benefit from the interaction of the State, and that some how the evidence for this is that all contries have experienced government interference in their economy:
I hope that by now you are getting the picture: she has taken a sample of all cubes and says there's no such thing as a circle. You must have a control group in any experiment - in this case it would involve looking at economies that were not controlled by the state. Since no such economy has ever lasted long, at least not recently, we have no data on that front. However, the Adam Smith Institute has an article that examines the next best thing - plotting economic prosperity against state interference in the economy, and it tells a rather different story:
 As you can see there is definitely a correlation there, and it doesn't come down in favour of state interference. I'm not going to call that a clinching argument - clearly there are other factors at play since for a freedom rating of 7, for example, there is a wide variance of GDP per capita, but it strongly supports the case that government interference is killing the economy, not helping it.
State “guidance” of the economy, in the broadest sense, is the shared history of all countries that have successfully industrialised.So, all countries have experienced state guidance of industry, their industry has grown, and this means that state guidance is a good thing. That's like saying that all people die, people are a good thing, therefore death is a good thing. All cats have four legs; my dog has four legs, therefore my dog is a cat.
... It is not that one set of countries practise “free-market capitalism” while another set practise “state-guided capitalism”. It is closer to the truth to point to the differing ways in which all economies – whether emerging or advanced – draw on state involvement in guiding and shaping development. It is recognition of this point that is long overdue in mainstream economic and political thinking.
... it has been the rapid rise of China and other emerging giants, India and Brazil – the so-called BICs — that has done more to challenge the Washington Consensus idea that state activism is always inimical to economic prosperity.
I hope that by now you are getting the picture: she has taken a sample of all cubes and says there's no such thing as a circle. You must have a control group in any experiment - in this case it would involve looking at economies that were not controlled by the state. Since no such economy has ever lasted long, at least not recently, we have no data on that front. However, the Adam Smith Institute has an article that examines the next best thing - plotting economic prosperity against state interference in the economy, and it tells a rather different story:
 As you can see there is definitely a correlation there, and it doesn't come down in favour of state interference. I'm not going to call that a clinching argument - clearly there are other factors at play since for a freedom rating of 7, for example, there is a wide variance of GDP per capita, but it strongly supports the case that government interference is killing the economy, not helping it.
Sunday, 8 January 2012
Unemployment theory
No, don't "turn over", you'll like it.
Recently I've been thinking about the causes of unemployment. I don't know a lot about the Austrian perspective on it, but no doubt there has been someone who has developed it. I want to come up with some ideas and see how they stack up.
The modern economists view inflation and unemployment as irreconcilable goals, since they believe that lowering inflation will increase uneployment and vice versa. Whether or not this is true under MMT I leave to other more capable minds than mine, but it does sort of make sense that if interest rates are high to keep inflation low then there is less money available for discretionary purchases and so you could see some short term unemployment shock.
Before we get into the details of what causes unemployment, however, it is enlightening to examine what situation would result in full employment. Firstly, I will consider such an economy as has a market money system, so forget about central banks and fractional reserves.
In a market economy everyone acts as an entrepreneur in every market transaction. All people are considering whether if they engage in a certain trade they will end up with more wealth than before. If the answer is yes, they trade, if not, they don't. Whether they have acted as a good entrepreneur is answered by whether they actually do end up with more wealth after the exchange than before. As I have mentioned previously, wealth is highly subjective and cannot be measured, so the only person who can know this is the one who made the trade. Money profit is easier to measure but it's only a small part of the picture. People donate money to charity not because they think they will receive something of cash value in return but because they have compassion for the needs of others and they feel better about being wealthy when others are not if they give some away.
In the same way, whenever someone is looking for work they are also acting as an entrepreneur. All people always want more goods and services, so it is impossible that there are simply no jobs available in the economy. It is simply foolish to say that jobs are "created" or "destroyed". Demand for labour flows from one region of the economy to another, but there is always infinite demand for labour and only a finite supply, and all regions of the economy always have infinite demand for it, so the prices for the labour control where it goes. When someone looks for work they are proposing to trade their labour for some price. If the utility of their labour is expected to be in some way low then they will usually get a low price for it. If it is high then they may demand high wages.
Now that we have some grip of the basics we can start to talk about unemployment. Firstly, unemployment is theoretically impossible. That is to say, there is always infinite demand for labour so how is it that anyone would ever be unemployed?
If the expected utility of someone's labour is very low then they might not be able to command wages even as low as the minimum wage, so in that case unemployment is the result of the minimum wage price control. So we have fact number one:
1. Minimum wage laws produce unemployment.
Now let us say that the Austrian view of the business cycle is broadly correct. In this case, when the economy shifts from high gear to low gear, there is a sudden drop in relative demand for labour in certain sectors of the economy, formerly booming. As a result those workers have to take a large drop in salary because the utility of their labour has become low, or there have to be layoffs. Fortunately for those driven below the breadline or the minimum wage line, there is always infinite demand for labour so they can move into other sectors of the economy. But now we have a problem, you see, because those people who were formerly skilled are now unskilled, so they have a low utility of labour and consequently low wages. Some might be only prepared to accept the same wages as before, until they capitulate, and this will also result in unemployment. Further, some jobs require years of training and this is usually chosen because of expected future demand in that sector. If someone trains as a civil engineer and an economic downturn puts construction on hold they will not be able to break into that labour market. As a result we can say that business cycles are responsible for unemployment, and since they in turn are caused by interest rate manipulation, we can say:
2. Interest rate manipulation causes unemployment.
We're not quite done with interest rates either, since there's something very few people know about them: they are a tax. Consider what the central bank in any country does if inflation is getting high: they increase interest rates. They way they do this is by decreasing availability of bank reserves by some boring way you needn't bother about. When they do this the cost of lending goes up for banks and the money creating process slows. In turn, banks increase their interest rates to encourage people to save and to make sure they stay profitable. There's one big fly in the ointment, though, and it's variable rate home loans. When interest rates go up these people's disposable income goes down, since more is needed to pay the bank because the banks costs have been increased by the central bank. As a result of this process, money is extracted from home loan payers and goes to the central bank, where the profit is sent to the government. In other words, interest rate changes are changes in a tax rate.
What has this to do with unemployment, I hear you ask? Well I am glad you asked because I now come to the third cause of unemployment. Any tax on the income of a business will cause that business to have to grow more slowly. Slower growth by definition means that it will be able to employ people only at a slower rate. This reduction in the rate of employee uptake can also cause people to stop working or move to sectors where they have little skill. Furthermore, individual income tax also reduces the rate of growth of business because it removes money available for discretionary spending that might have been spent on consumer goods. Thus we come to number three:
3. Taxes cause unemployment.
In fact, anything that distorts the economy, makes it hard to predict or extracts wealth from it will cause unemployment in some measure. And let's not forget what happens to the wealth extracted from the economy: a large part of it is given to the unemployed. This might seem like a great thing but in fact it lessens their desire to get a job again. This disincentive to work is at the heart of number four:
4. Unemployment benefits cause unemployment.
These four things - where do they come from? Are they produced by the market? Well, no. All of these are laws, functions or impositions of government, by government, for government. So we can create a new statement zero about unemployment:
0. State interference in the market causes unemployment.
Still think Obama's jobs plan might have worked?
Recently I've been thinking about the causes of unemployment. I don't know a lot about the Austrian perspective on it, but no doubt there has been someone who has developed it. I want to come up with some ideas and see how they stack up.
The modern economists view inflation and unemployment as irreconcilable goals, since they believe that lowering inflation will increase uneployment and vice versa. Whether or not this is true under MMT I leave to other more capable minds than mine, but it does sort of make sense that if interest rates are high to keep inflation low then there is less money available for discretionary purchases and so you could see some short term unemployment shock.
Before we get into the details of what causes unemployment, however, it is enlightening to examine what situation would result in full employment. Firstly, I will consider such an economy as has a market money system, so forget about central banks and fractional reserves.
In a market economy everyone acts as an entrepreneur in every market transaction. All people are considering whether if they engage in a certain trade they will end up with more wealth than before. If the answer is yes, they trade, if not, they don't. Whether they have acted as a good entrepreneur is answered by whether they actually do end up with more wealth after the exchange than before. As I have mentioned previously, wealth is highly subjective and cannot be measured, so the only person who can know this is the one who made the trade. Money profit is easier to measure but it's only a small part of the picture. People donate money to charity not because they think they will receive something of cash value in return but because they have compassion for the needs of others and they feel better about being wealthy when others are not if they give some away.
In the same way, whenever someone is looking for work they are also acting as an entrepreneur. All people always want more goods and services, so it is impossible that there are simply no jobs available in the economy. It is simply foolish to say that jobs are "created" or "destroyed". Demand for labour flows from one region of the economy to another, but there is always infinite demand for labour and only a finite supply, and all regions of the economy always have infinite demand for it, so the prices for the labour control where it goes. When someone looks for work they are proposing to trade their labour for some price. If the utility of their labour is expected to be in some way low then they will usually get a low price for it. If it is high then they may demand high wages.
Now that we have some grip of the basics we can start to talk about unemployment. Firstly, unemployment is theoretically impossible. That is to say, there is always infinite demand for labour so how is it that anyone would ever be unemployed?
If the expected utility of someone's labour is very low then they might not be able to command wages even as low as the minimum wage, so in that case unemployment is the result of the minimum wage price control. So we have fact number one:
1. Minimum wage laws produce unemployment.
Now let us say that the Austrian view of the business cycle is broadly correct. In this case, when the economy shifts from high gear to low gear, there is a sudden drop in relative demand for labour in certain sectors of the economy, formerly booming. As a result those workers have to take a large drop in salary because the utility of their labour has become low, or there have to be layoffs. Fortunately for those driven below the breadline or the minimum wage line, there is always infinite demand for labour so they can move into other sectors of the economy. But now we have a problem, you see, because those people who were formerly skilled are now unskilled, so they have a low utility of labour and consequently low wages. Some might be only prepared to accept the same wages as before, until they capitulate, and this will also result in unemployment. Further, some jobs require years of training and this is usually chosen because of expected future demand in that sector. If someone trains as a civil engineer and an economic downturn puts construction on hold they will not be able to break into that labour market. As a result we can say that business cycles are responsible for unemployment, and since they in turn are caused by interest rate manipulation, we can say:
2. Interest rate manipulation causes unemployment.
We're not quite done with interest rates either, since there's something very few people know about them: they are a tax. Consider what the central bank in any country does if inflation is getting high: they increase interest rates. They way they do this is by decreasing availability of bank reserves by some boring way you needn't bother about. When they do this the cost of lending goes up for banks and the money creating process slows. In turn, banks increase their interest rates to encourage people to save and to make sure they stay profitable. There's one big fly in the ointment, though, and it's variable rate home loans. When interest rates go up these people's disposable income goes down, since more is needed to pay the bank because the banks costs have been increased by the central bank. As a result of this process, money is extracted from home loan payers and goes to the central bank, where the profit is sent to the government. In other words, interest rate changes are changes in a tax rate.
What has this to do with unemployment, I hear you ask? Well I am glad you asked because I now come to the third cause of unemployment. Any tax on the income of a business will cause that business to have to grow more slowly. Slower growth by definition means that it will be able to employ people only at a slower rate. This reduction in the rate of employee uptake can also cause people to stop working or move to sectors where they have little skill. Furthermore, individual income tax also reduces the rate of growth of business because it removes money available for discretionary spending that might have been spent on consumer goods. Thus we come to number three:
3. Taxes cause unemployment.
In fact, anything that distorts the economy, makes it hard to predict or extracts wealth from it will cause unemployment in some measure. And let's not forget what happens to the wealth extracted from the economy: a large part of it is given to the unemployed. This might seem like a great thing but in fact it lessens their desire to get a job again. This disincentive to work is at the heart of number four:
4. Unemployment benefits cause unemployment.
These four things - where do they come from? Are they produced by the market? Well, no. All of these are laws, functions or impositions of government, by government, for government. So we can create a new statement zero about unemployment:
0. State interference in the market causes unemployment.
Still think Obama's jobs plan might have worked?
Thursday, 29 December 2011
What is wealth?
I once heard Jörg Guido Hülsmann say that there is no nice, clear definition of what an economic good is. I do sort of agree with that. What is a good? Something that provides some benefit? Dictionary.com says:


I think we can be a little more creative than that. Here's my definition of wealth:
Examples of economic wealth might be a house, or manufacturing plants. Examples of non economic wealth are when things start to get interesting. Your spouse is part of your wealth. So are you children and your parents, your friends and so on. They all (hopefully) make your life better in some way, so they are included in wealth, but you can't buy love. Love you give also makes you wealthy since it increases your contentment with life and the joy you have with your friends or family. If you value these things more than all economic goods, then you are by definition more wealthy than the chairman of a bank (provided that he cares less for his family or friends). Most people would not trade their families for even extraordinary economic wealth, which proves that they value them more.
Now I want to highlight one of the most important aspects of Christianity. Anyone who has God is so wealthy that no friend, family, money or any other thing can significantly improve his wealth. That is not to say that those things have no value, but compared to God, they have insignificant value. That is one of the reasons that Jesus says, "If anyone comes to me and does not hate his father and mother, his wife and children, his brothers and sisters--yes, even his own life--he cannot be my disciple." He doesn't actually mean that we should hate those people, or our own life. What He does mean is that the value we place on following Him must always be greater than on any other thing - relationships, even life itself. Because to have Him is the greatest good of all and nothing else can compare. He's just asking us to recognise that fact and act on it.
OK, so it satisfies human wants and as a result it has some value in exchange. I want to explore a broader definition: wealth. Normally we think of people who earn a lot of money as wealthy. They often buy expensive houses and cars, perhaps a nice yacht or Gulfstream jet.


Pictured above: wealth?
I think we can be a little more creative than that. Here's my definition of wealth:
Wealth is any factor that gives ease.Short, I know, but it has some pretty important implications. First of all, there are two types of wealth: that which can be bought and that which cannot, in other words economic goods and other things that don't have a price but nevertheless give some satisfaction.
Examples of economic wealth might be a house, or manufacturing plants. Examples of non economic wealth are when things start to get interesting. Your spouse is part of your wealth. So are you children and your parents, your friends and so on. They all (hopefully) make your life better in some way, so they are included in wealth, but you can't buy love. Love you give also makes you wealthy since it increases your contentment with life and the joy you have with your friends or family. If you value these things more than all economic goods, then you are by definition more wealthy than the chairman of a bank (provided that he cares less for his family or friends). Most people would not trade their families for even extraordinary economic wealth, which proves that they value them more.
Now I want to highlight one of the most important aspects of Christianity. Anyone who has God is so wealthy that no friend, family, money or any other thing can significantly improve his wealth. That is not to say that those things have no value, but compared to God, they have insignificant value. That is one of the reasons that Jesus says, "If anyone comes to me and does not hate his father and mother, his wife and children, his brothers and sisters--yes, even his own life--he cannot be my disciple." He doesn't actually mean that we should hate those people, or our own life. What He does mean is that the value we place on following Him must always be greater than on any other thing - relationships, even life itself. Because to have Him is the greatest good of all and nothing else can compare. He's just asking us to recognise that fact and act on it.
Sunday, 7 August 2011
Boom and Bust
Anyone unfortunate enough to stumble across my blog may be led to believe that I have no time or inclination for writing - after all, if I did there would be more posts, wouldn't there? The truth is rather different - I find it hard to choose what to write about, because it seems there are so many topics that urgently require my inspection. As a result I may make extensive notes about an idea and then never use it. It is a fact that I have fairly recently returned my appetite for knowledge so I must be a nett consumer of information if I am to get anywhere with anything. Hopefully I can return the fruits of my investigations to whoever is willing to read.
Lately I've been bending my will towards understanding economics. It seems that he field is muddy even to the experts, and assumptions and pitfalls abound. The 2008 crash showed that the banks didn't really know what they were doing, and before the crisis everyone thought the world was hunky-dory, so no-one else knew either, except a few like this guy. In fact I would hazard a guess that no one really knows what causes things like inflation, bubbles, deflation, crashes and the like. All we know is that generally if we put pressure on point x we get a response y. Thus when a country's official interest rate is lowered, inflation increases, and vice versa.
Most of today's economy seems to revolve around investors, in one way or another. The thinking is that no investor will willingly throw money away by buying into a bad deal, but the crash of 2008 showed this belief to be a fantasy. Governments can borrow money because investors are willing to give it to them - if they expect a return. Currencies are strengthen or weaken depending on how much faith investors have that the currency will stay strong or will weaken further. Companies can borrow money if banks think they will get a nett return, same for individuals. Investors bank money if they think the bank's practices are lucrative.
It does not take long to realise that this whole thing is a positive feedback loop. It all works if people are confident, but it rapidly goes down the toilet if people lose confidence. Granted this is a simplification but let's work with it for a moment. What are the checks? Where is the point where investment confidence is lost? Where is it gained? This article lists some of the causes and effects of four major crashes over the last century or so. They all have in common the formation of a "bubble" leading up to the crash. The first three have new rules associated with them that were intended to prevent future crashes. All of them failed. The Economists apparently ran out of talent, too, because no additional rules or institutions have resulted from the most recent crash, in order to prevent such a thing happening again. Instead we had costly bailouts, humiliatingly paid for by countries we might consider backward - China and the oil nations of the Middle East. In fact China is now the US's biggest creditor. The crashes we have suffered were either necessary, or they should direct us to restructure our finance. No one is claiming they were necessary and the Arab world laughed at us, saying their financial structures were more robust. So have we changed the way we do business? I should coco.
You may think I am having a downer on investors - after all, they are the link in the chain that has the most influence on the positive feedback - but I'm not, really. They are part of the problem but they are not the problem. The real problem is the way we do business. This article and the comments it sparked have some very interesting views, and suggest some solutions that are presently beyond me. It suggests that financial engineers are to blame for the crash, and to an extent they may be, but what is it about the system that makes financial engineering a tempting prospect in the first place? Why do bubbles form at all?
The answers to those questions are by no means obvious, and there is debate among economists on the answers. There are some things we can say with a reasonable degree of conviction, though. Firstly both the bubble and the crash are in principle based on investor psychology. It doesn't seem possible to identify one particular cause, instead a range of factors come into play.
A bubble is a type of inflation, except that in the real world if inflation causes a rise in the cost of, say, electricity, each kWh still has a genuine worth based on the production and distribution cost. Its worth is anchored in the work required to create it and get it into your house, or factory, or whatever. Of course demand can increase its price, but ultimately its worth can never go much above the economic benefit it gives to the buyer. Stocks, too, are subject to supply and demand. When a company is goes public its apparent worth is divided among stocks or shares, giving each of those shares a value that is defined by the total value of the company. The money raised from this partial sale is used to further the business. Over time the stocks of the company increase or decrease in value as investors buy or sell depending on whether they believe the company is growing or shrinking. Bad news, such as under-target profits, tend to depress the value of stock, and vice versa. But ultimately the real-terms value of stock is not known, it is only inferred from the company's past performance, market conditions and the company's current performance. So if investors suddenly believed that a company was going down the tubes they might sell all the public stock back to the company, resulting in a price drop that might make going down the tubes inevitable. A self-fulfilling prophecy. There is no anchor for the value of stocks, they are worth exactly what investors think they are worth. This becomes a problem when investors' beliefs are based on the beliefs of other investors. This was illustrated nicely when the dotcom bubble ocurred. Investors were so confident in the new business model that they thought such companies were worth more than their real value, resulting in a runaway investment boom that ended when everybody realised it was chaff. Some people legally made shed loads of cash by taking advantage of the investors' credulity. There is a word for such people. It is "conman". More can be found here. Similarly the bubble bursts when investors realise the bubble can no longer be sustained and opt out. A "correction" results, which, if the number of investors in the bubble is large enough, can become a crash, as investors with no exit strategy panic and sell as fast as possible to avoid heavy losses.
The model allows for rapid increases in stock prices, thus growing a company very fast, which can be a good thing, for sure, but this very volatility also gives rise to the possibility of a massive crash, resulting in a company losing value, likely ending up being undervalued. Instability is inherent in the system, so we either have to accept that crashes will occur and hope that the times of plenty make up for them, or we have to design a new system where stock valuations are not so volatile.
Lately I've been bending my will towards understanding economics. It seems that he field is muddy even to the experts, and assumptions and pitfalls abound. The 2008 crash showed that the banks didn't really know what they were doing, and before the crisis everyone thought the world was hunky-dory, so no-one else knew either, except a few like this guy. In fact I would hazard a guess that no one really knows what causes things like inflation, bubbles, deflation, crashes and the like. All we know is that generally if we put pressure on point x we get a response y. Thus when a country's official interest rate is lowered, inflation increases, and vice versa.
Most of today's economy seems to revolve around investors, in one way or another. The thinking is that no investor will willingly throw money away by buying into a bad deal, but the crash of 2008 showed this belief to be a fantasy. Governments can borrow money because investors are willing to give it to them - if they expect a return. Currencies are strengthen or weaken depending on how much faith investors have that the currency will stay strong or will weaken further. Companies can borrow money if banks think they will get a nett return, same for individuals. Investors bank money if they think the bank's practices are lucrative.
It does not take long to realise that this whole thing is a positive feedback loop. It all works if people are confident, but it rapidly goes down the toilet if people lose confidence. Granted this is a simplification but let's work with it for a moment. What are the checks? Where is the point where investment confidence is lost? Where is it gained? This article lists some of the causes and effects of four major crashes over the last century or so. They all have in common the formation of a "bubble" leading up to the crash. The first three have new rules associated with them that were intended to prevent future crashes. All of them failed. The Economists apparently ran out of talent, too, because no additional rules or institutions have resulted from the most recent crash, in order to prevent such a thing happening again. Instead we had costly bailouts, humiliatingly paid for by countries we might consider backward - China and the oil nations of the Middle East. In fact China is now the US's biggest creditor. The crashes we have suffered were either necessary, or they should direct us to restructure our finance. No one is claiming they were necessary and the Arab world laughed at us, saying their financial structures were more robust. So have we changed the way we do business? I should coco.
You may think I am having a downer on investors - after all, they are the link in the chain that has the most influence on the positive feedback - but I'm not, really. They are part of the problem but they are not the problem. The real problem is the way we do business. This article and the comments it sparked have some very interesting views, and suggest some solutions that are presently beyond me. It suggests that financial engineers are to blame for the crash, and to an extent they may be, but what is it about the system that makes financial engineering a tempting prospect in the first place? Why do bubbles form at all?
The answers to those questions are by no means obvious, and there is debate among economists on the answers. There are some things we can say with a reasonable degree of conviction, though. Firstly both the bubble and the crash are in principle based on investor psychology. It doesn't seem possible to identify one particular cause, instead a range of factors come into play.
A bubble is a type of inflation, except that in the real world if inflation causes a rise in the cost of, say, electricity, each kWh still has a genuine worth based on the production and distribution cost. Its worth is anchored in the work required to create it and get it into your house, or factory, or whatever. Of course demand can increase its price, but ultimately its worth can never go much above the economic benefit it gives to the buyer. Stocks, too, are subject to supply and demand. When a company is goes public its apparent worth is divided among stocks or shares, giving each of those shares a value that is defined by the total value of the company. The money raised from this partial sale is used to further the business. Over time the stocks of the company increase or decrease in value as investors buy or sell depending on whether they believe the company is growing or shrinking. Bad news, such as under-target profits, tend to depress the value of stock, and vice versa. But ultimately the real-terms value of stock is not known, it is only inferred from the company's past performance, market conditions and the company's current performance. So if investors suddenly believed that a company was going down the tubes they might sell all the public stock back to the company, resulting in a price drop that might make going down the tubes inevitable. A self-fulfilling prophecy. There is no anchor for the value of stocks, they are worth exactly what investors think they are worth. This becomes a problem when investors' beliefs are based on the beliefs of other investors. This was illustrated nicely when the dotcom bubble ocurred. Investors were so confident in the new business model that they thought such companies were worth more than their real value, resulting in a runaway investment boom that ended when everybody realised it was chaff. Some people legally made shed loads of cash by taking advantage of the investors' credulity. There is a word for such people. It is "conman". More can be found here. Similarly the bubble bursts when investors realise the bubble can no longer be sustained and opt out. A "correction" results, which, if the number of investors in the bubble is large enough, can become a crash, as investors with no exit strategy panic and sell as fast as possible to avoid heavy losses.
The model allows for rapid increases in stock prices, thus growing a company very fast, which can be a good thing, for sure, but this very volatility also gives rise to the possibility of a massive crash, resulting in a company losing value, likely ending up being undervalued. Instability is inherent in the system, so we either have to accept that crashes will occur and hope that the times of plenty make up for them, or we have to design a new system where stock valuations are not so volatile.
Subscribe to:
Posts (Atom)