A few days ago was the last call for entries to the Wolfson economics Prize. I'd quite like to have entered but I didn't really find out about it in time to put together a decent offering. So here's the short version of my plan for how you can unwind the Euro.
With all the problems faced by the country and financial contraction, capital flowing out, all of those very damaging things, the Greek economy will soon be an inch from death. The way to reverse that trend is to make Greece suddenly the best place in the world to do business. Austerity will do the exact opposite of that (even the IMF, which insisted on austerity in the first place, is saying that), as will the flight of the Greek people out of Greece. If Greece simply adopts its own currency then there will be a run on that currency as every Greek moves his or her money out of the country to keep it safe from inflation. The inevitable result is hyperinflation, according to the theory I put forth in earlier blog posts. There is a way around all of this and it's going to sound really weird to most economists. You don't actually have to abolish the Euro at all. That brings me neatly to my plan of action.
Phase 1: Introduce competition
Currency competition, that is. The only reason the Euro is used at all is that it's illegal to use anything else. If you lifted that restriction without providing an alternative then the market would bring in gold and silver money. This is the reverse mode of Gresham's Law. I don't even mind if they use the exact same trimetallic system I talked about in an earlier post. This money would not require legal tender status because everyone would accept it without government fiat. The process of adoption could be greatly accelerated by waiving taxes on transactions using any currency other than the Euro, although I doubt this incentive would be needed. The market will take care of all minting, changing of coin operated machines of all kinds and so on without any need for government money. The parallel currency would soften the transition away from the Euro because of the buffer effect of the limits of the rate of flow of new money into Greece. The equipment to mint the large number of coins required for commerce would not spring up overnight, and the rate of minting is also limited by how quickly gold and silver may be transported into Greece. Due to the popularity of the new money it would greatly increase the prices of gold and silver in Greece with respect to the Euro, and thereby in the rest of the world through international trade. Euros would flow out and precious metals in, supplanting the supply of Euros in a seamless transition while commerce suffers no negative effects.
Phase 2: Bonds
The spike in gold price caused by its restoration to money status will make early adopters immensely wealthy, increasing the adoption of gold as currency and flushing the Euro out of the country. The government would know all this and should therefore start with a substantial gold position, selling it to the populace in exchange for their Euros. The rise of gold price will allow the government to sell at ever greater prices and extract enough Euros out of the Greeks to pay down the bonds. Again this will not interfere in commerce in a negative sense. The government would buy back all Euro denominated bonds issued in the market and simply cancel those held by the central bank, thus eliminating its foreign debt. The brief was to have all parties happy, but this is simply impossible. Currently banks and stock markets are living off the hard work of ordinary people, and this has to stop. It necessitates a transfer of capital from the inflated stockmarkets, bloated government balance sheets, and other bubble assets back to the average citizen - capital which rightfully belongs to those that earn it. However this will no doubt enrage those for whom the party is over and whose speculation has to find avenues in less enlightened countries. Those institutions that benefited under the debt monetisation fraud must necessarily suffer the most when such schemes are unwound. That is simply justice.
Government finance during Phase 2
The initial gold position of the Greek government is crucial for maintaining solvency throughout the most turbulent transitions of phase two. The Euros they obtain by selling gold to the Greek people will serve not only to buy more gold on foreign exchange and eliminate the bonds but to enable the continuity of certain government services, namely police and infrastructure. This period of probably half a year must be funded entirely by the appreciation in the price of gold with respect to the Euro, so the government should act shrewdly in when it chooses to start selling its gold. By the end it should have no permanent store of gold but for an emergency fund of gold currency and that required for the day to day running of government business, funded entirely by tax revenue. Its revenue must then remain neutral.
Phase 3: The Greek Euro
Phase three will happen naturally. Either the Greek government will see reason and end parity with other Euro currency or the governments of all other nations will stop accepting Greek currency at parity. The latter is more likely given the Greek government's incentive to keep the currency at parity to allow rapid debt payment. At this point the Greek Euro will experience a rapid drop in value. Hyperinflation of the Greek Euro will occur, but this time it won't hurt anyone since most people will already be using specie currency. The economy will be intact. On the same day that parity is canceled, the Greek government would start requiring taxes in the new specie currency. Its tax rate would be very low to begin with, say 5% flat income tax, in order to promote growth. Most of the non essential government staff would have left the public sector because their Greek Euro denominated salaries would have been losing value.
Phase 4: Exit the Euro
Yep, it really is that simple. Once the specie money has pretty well totally displaced the old Euro currency, all that is left is for the Greek government and central bank to say, well, we tried but the people didn't want the Euro, sorry, and stop issuing it. They can then munch up all the old currency in shredders and save a few notes to sell to collectors some years on to remind everyone of the bad old days.
Impact on other Eurozone countries
Phase 1 will lead to some substantial appreciation of the price of gold and silver as the Greek people stop accepting Euros so they don't have to pay tax. The Euro money supply of Greece will disperse into neighbouring countries if they are still accepting the Greek currency, and be absorbed by Greek banks if not. Germany, China, US, India and other countries with large gold positions would gain substantial boosts to their wealth as gold returned to its monetary use in Greece. Needless to say, this effect would be compounded multiply if many countries went a similar way.
Phase 2 would have a slight negative effect on banks but as it will be relatively gradual the effect would be time dissipated. Bond buybacks would continue throughout the initial adjustment period. Most Greek bonds are held by banks, central or otherwise, which can absorb the drop in the value of those bonds. Greece herself would be unaffected by the huge spike in yield because she would no longer be issuing any new bonds. In fact, the yield spike would make it all the easier to buy the debt. Some pension funds also hold Euro denominated Greek debt, and as a result some people would suffer loss there but it is a relatively small amount. If a country such as the US decided to return to the PM standard in this way many investors would be wiped out as US Treasuries fell in value. This is an unfortunate but unavoidable step in the move back to sound money. It cannot be guaranteed that all those that benefited from inflation will suffer in deflation, as would justly be the case.
During Phase 3 the transition will be largely complete and there will be no one left to complain of hyperinflation. Taxes would begin to flow back to a public sector composed of only very few people. With the econonmy back in balance and very likely booming hugely the government could return to the business of providing a police force and certain utilities.
Phase 4 would have minimal effects, it is merely a technical end to the Euro era for Greece.
In summary, this method of exiting a debt monetised fiat currency is most likely the only way of smoothly transitioning out of such a currency, or as smooth as a currency transition can be. There is no way of making such a massive change without short changing some people along the way, but my favoured method is to allow the market to clear, withdraw government influence from currency, and all of Austrian theory says that the result will be the most equitable transition possible. The new currency is in fact a by-product of allowing people to choose how they buy and sell, and what they use to buy and sell. This makes it the most liberal of all possible schemes, and where liberty and justice thrive, wealth is sure to follow.
Wednesday, 18 January 2012

Sunday, 8 January 2012
Unemployment theory
No, don't "turn over", you'll like it.
Recently I've been thinking about the causes of unemployment. I don't know a lot about the Austrian perspective on it, but no doubt there has been someone who has developed it. I want to come up with some ideas and see how they stack up.
The modern economists view inflation and unemployment as irreconcilable goals, since they believe that lowering inflation will increase uneployment and vice versa. Whether or not this is true under MMT I leave to other more capable minds than mine, but it does sort of make sense that if interest rates are high to keep inflation low then there is less money available for discretionary purchases and so you could see some short term unemployment shock.
Before we get into the details of what causes unemployment, however, it is enlightening to examine what situation would result in full employment. Firstly, I will consider such an economy as has a market money system, so forget about central banks and fractional reserves.
In a market economy everyone acts as an entrepreneur in every market transaction. All people are considering whether if they engage in a certain trade they will end up with more wealth than before. If the answer is yes, they trade, if not, they don't. Whether they have acted as a good entrepreneur is answered by whether they actually do end up with more wealth after the exchange than before. As I have mentioned previously, wealth is highly subjective and cannot be measured, so the only person who can know this is the one who made the trade. Money profit is easier to measure but it's only a small part of the picture. People donate money to charity not because they think they will receive something of cash value in return but because they have compassion for the needs of others and they feel better about being wealthy when others are not if they give some away.
In the same way, whenever someone is looking for work they are also acting as an entrepreneur. All people always want more goods and services, so it is impossible that there are simply no jobs available in the economy. It is simply foolish to say that jobs are "created" or "destroyed". Demand for labour flows from one region of the economy to another, but there is always infinite demand for labour and only a finite supply, and all regions of the economy always have infinite demand for it, so the prices for the labour control where it goes. When someone looks for work they are proposing to trade their labour for some price. If the utility of their labour is expected to be in some way low then they will usually get a low price for it. If it is high then they may demand high wages.
Now that we have some grip of the basics we can start to talk about unemployment. Firstly, unemployment is theoretically impossible. That is to say, there is always infinite demand for labour so how is it that anyone would ever be unemployed?
If the expected utility of someone's labour is very low then they might not be able to command wages even as low as the minimum wage, so in that case unemployment is the result of the minimum wage price control. So we have fact number one:
1. Minimum wage laws produce unemployment.
Now let us say that the Austrian view of the business cycle is broadly correct. In this case, when the economy shifts from high gear to low gear, there is a sudden drop in relative demand for labour in certain sectors of the economy, formerly booming. As a result those workers have to take a large drop in salary because the utility of their labour has become low, or there have to be layoffs. Fortunately for those driven below the breadline or the minimum wage line, there is always infinite demand for labour so they can move into other sectors of the economy. But now we have a problem, you see, because those people who were formerly skilled are now unskilled, so they have a low utility of labour and consequently low wages. Some might be only prepared to accept the same wages as before, until they capitulate, and this will also result in unemployment. Further, some jobs require years of training and this is usually chosen because of expected future demand in that sector. If someone trains as a civil engineer and an economic downturn puts construction on hold they will not be able to break into that labour market. As a result we can say that business cycles are responsible for unemployment, and since they in turn are caused by interest rate manipulation, we can say:
2. Interest rate manipulation causes unemployment.
We're not quite done with interest rates either, since there's something very few people know about them: they are a tax. Consider what the central bank in any country does if inflation is getting high: they increase interest rates. They way they do this is by decreasing availability of bank reserves by some boring way you needn't bother about. When they do this the cost of lending goes up for banks and the money creating process slows. In turn, banks increase their interest rates to encourage people to save and to make sure they stay profitable. There's one big fly in the ointment, though, and it's variable rate home loans. When interest rates go up these people's disposable income goes down, since more is needed to pay the bank because the banks costs have been increased by the central bank. As a result of this process, money is extracted from home loan payers and goes to the central bank, where the profit is sent to the government. In other words, interest rate changes are changes in a tax rate.
What has this to do with unemployment, I hear you ask? Well I am glad you asked because I now come to the third cause of unemployment. Any tax on the income of a business will cause that business to have to grow more slowly. Slower growth by definition means that it will be able to employ people only at a slower rate. This reduction in the rate of employee uptake can also cause people to stop working or move to sectors where they have little skill. Furthermore, individual income tax also reduces the rate of growth of business because it removes money available for discretionary spending that might have been spent on consumer goods. Thus we come to number three:
3. Taxes cause unemployment.
In fact, anything that distorts the economy, makes it hard to predict or extracts wealth from it will cause unemployment in some measure. And let's not forget what happens to the wealth extracted from the economy: a large part of it is given to the unemployed. This might seem like a great thing but in fact it lessens their desire to get a job again. This disincentive to work is at the heart of number four:
4. Unemployment benefits cause unemployment.
These four things - where do they come from? Are they produced by the market? Well, no. All of these are laws, functions or impositions of government, by government, for government. So we can create a new statement zero about unemployment:
0. State interference in the market causes unemployment.
Still think Obama's jobs plan might have worked?
Recently I've been thinking about the causes of unemployment. I don't know a lot about the Austrian perspective on it, but no doubt there has been someone who has developed it. I want to come up with some ideas and see how they stack up.
The modern economists view inflation and unemployment as irreconcilable goals, since they believe that lowering inflation will increase uneployment and vice versa. Whether or not this is true under MMT I leave to other more capable minds than mine, but it does sort of make sense that if interest rates are high to keep inflation low then there is less money available for discretionary purchases and so you could see some short term unemployment shock.
Before we get into the details of what causes unemployment, however, it is enlightening to examine what situation would result in full employment. Firstly, I will consider such an economy as has a market money system, so forget about central banks and fractional reserves.
In a market economy everyone acts as an entrepreneur in every market transaction. All people are considering whether if they engage in a certain trade they will end up with more wealth than before. If the answer is yes, they trade, if not, they don't. Whether they have acted as a good entrepreneur is answered by whether they actually do end up with more wealth after the exchange than before. As I have mentioned previously, wealth is highly subjective and cannot be measured, so the only person who can know this is the one who made the trade. Money profit is easier to measure but it's only a small part of the picture. People donate money to charity not because they think they will receive something of cash value in return but because they have compassion for the needs of others and they feel better about being wealthy when others are not if they give some away.
In the same way, whenever someone is looking for work they are also acting as an entrepreneur. All people always want more goods and services, so it is impossible that there are simply no jobs available in the economy. It is simply foolish to say that jobs are "created" or "destroyed". Demand for labour flows from one region of the economy to another, but there is always infinite demand for labour and only a finite supply, and all regions of the economy always have infinite demand for it, so the prices for the labour control where it goes. When someone looks for work they are proposing to trade their labour for some price. If the utility of their labour is expected to be in some way low then they will usually get a low price for it. If it is high then they may demand high wages.
Now that we have some grip of the basics we can start to talk about unemployment. Firstly, unemployment is theoretically impossible. That is to say, there is always infinite demand for labour so how is it that anyone would ever be unemployed?
If the expected utility of someone's labour is very low then they might not be able to command wages even as low as the minimum wage, so in that case unemployment is the result of the minimum wage price control. So we have fact number one:
1. Minimum wage laws produce unemployment.
Now let us say that the Austrian view of the business cycle is broadly correct. In this case, when the economy shifts from high gear to low gear, there is a sudden drop in relative demand for labour in certain sectors of the economy, formerly booming. As a result those workers have to take a large drop in salary because the utility of their labour has become low, or there have to be layoffs. Fortunately for those driven below the breadline or the minimum wage line, there is always infinite demand for labour so they can move into other sectors of the economy. But now we have a problem, you see, because those people who were formerly skilled are now unskilled, so they have a low utility of labour and consequently low wages. Some might be only prepared to accept the same wages as before, until they capitulate, and this will also result in unemployment. Further, some jobs require years of training and this is usually chosen because of expected future demand in that sector. If someone trains as a civil engineer and an economic downturn puts construction on hold they will not be able to break into that labour market. As a result we can say that business cycles are responsible for unemployment, and since they in turn are caused by interest rate manipulation, we can say:
2. Interest rate manipulation causes unemployment.
We're not quite done with interest rates either, since there's something very few people know about them: they are a tax. Consider what the central bank in any country does if inflation is getting high: they increase interest rates. They way they do this is by decreasing availability of bank reserves by some boring way you needn't bother about. When they do this the cost of lending goes up for banks and the money creating process slows. In turn, banks increase their interest rates to encourage people to save and to make sure they stay profitable. There's one big fly in the ointment, though, and it's variable rate home loans. When interest rates go up these people's disposable income goes down, since more is needed to pay the bank because the banks costs have been increased by the central bank. As a result of this process, money is extracted from home loan payers and goes to the central bank, where the profit is sent to the government. In other words, interest rate changes are changes in a tax rate.
What has this to do with unemployment, I hear you ask? Well I am glad you asked because I now come to the third cause of unemployment. Any tax on the income of a business will cause that business to have to grow more slowly. Slower growth by definition means that it will be able to employ people only at a slower rate. This reduction in the rate of employee uptake can also cause people to stop working or move to sectors where they have little skill. Furthermore, individual income tax also reduces the rate of growth of business because it removes money available for discretionary spending that might have been spent on consumer goods. Thus we come to number three:
3. Taxes cause unemployment.
In fact, anything that distorts the economy, makes it hard to predict or extracts wealth from it will cause unemployment in some measure. And let's not forget what happens to the wealth extracted from the economy: a large part of it is given to the unemployed. This might seem like a great thing but in fact it lessens their desire to get a job again. This disincentive to work is at the heart of number four:
4. Unemployment benefits cause unemployment.
These four things - where do they come from? Are they produced by the market? Well, no. All of these are laws, functions or impositions of government, by government, for government. So we can create a new statement zero about unemployment:
0. State interference in the market causes unemployment.
Still think Obama's jobs plan might have worked?
Thursday, 29 December 2011
What is wealth?
I once heard Jörg Guido Hülsmann say that there is no nice, clear definition of what an economic good is. I do sort of agree with that. What is a good? Something that provides some benefit? Dictionary.com says:


I think we can be a little more creative than that. Here's my definition of wealth:
Examples of economic wealth might be a house, or manufacturing plants. Examples of non economic wealth are when things start to get interesting. Your spouse is part of your wealth. So are you children and your parents, your friends and so on. They all (hopefully) make your life better in some way, so they are included in wealth, but you can't buy love. Love you give also makes you wealthy since it increases your contentment with life and the joy you have with your friends or family. If you value these things more than all economic goods, then you are by definition more wealthy than the chairman of a bank (provided that he cares less for his family or friends). Most people would not trade their families for even extraordinary economic wealth, which proves that they value them more.
Now I want to highlight one of the most important aspects of Christianity. Anyone who has God is so wealthy that no friend, family, money or any other thing can significantly improve his wealth. That is not to say that those things have no value, but compared to God, they have insignificant value. That is one of the reasons that Jesus says, "If anyone comes to me and does not hate his father and mother, his wife and children, his brothers and sisters--yes, even his own life--he cannot be my disciple." He doesn't actually mean that we should hate those people, or our own life. What He does mean is that the value we place on following Him must always be greater than on any other thing - relationships, even life itself. Because to have Him is the greatest good of all and nothing else can compare. He's just asking us to recognise that fact and act on it.
OK, so it satisfies human wants and as a result it has some value in exchange. I want to explore a broader definition: wealth. Normally we think of people who earn a lot of money as wealthy. They often buy expensive houses and cars, perhaps a nice yacht or Gulfstream jet.


Pictured above: wealth?
I think we can be a little more creative than that. Here's my definition of wealth:
Wealth is any factor that gives ease.Short, I know, but it has some pretty important implications. First of all, there are two types of wealth: that which can be bought and that which cannot, in other words economic goods and other things that don't have a price but nevertheless give some satisfaction.
Examples of economic wealth might be a house, or manufacturing plants. Examples of non economic wealth are when things start to get interesting. Your spouse is part of your wealth. So are you children and your parents, your friends and so on. They all (hopefully) make your life better in some way, so they are included in wealth, but you can't buy love. Love you give also makes you wealthy since it increases your contentment with life and the joy you have with your friends or family. If you value these things more than all economic goods, then you are by definition more wealthy than the chairman of a bank (provided that he cares less for his family or friends). Most people would not trade their families for even extraordinary economic wealth, which proves that they value them more.
Now I want to highlight one of the most important aspects of Christianity. Anyone who has God is so wealthy that no friend, family, money or any other thing can significantly improve his wealth. That is not to say that those things have no value, but compared to God, they have insignificant value. That is one of the reasons that Jesus says, "If anyone comes to me and does not hate his father and mother, his wife and children, his brothers and sisters--yes, even his own life--he cannot be my disciple." He doesn't actually mean that we should hate those people, or our own life. What He does mean is that the value we place on following Him must always be greater than on any other thing - relationships, even life itself. Because to have Him is the greatest good of all and nothing else can compare. He's just asking us to recognise that fact and act on it.
Wednesday, 28 December 2011
Fallacies of the eugenicists
Eugenics has a pretty bad reputation, but at the centre it's just people who want to make the world a better, more resilient place. Well, um, not, actually, that's not really true. Eugenicists take the view that modern society has a lot of substandard genetic stock floating around, making babies, and that this is a Bad Thing. It's a Bad Thing because that means that the good, strong people are having their genes diluted by the weak, feeble-minded majority, and this means that we will be more easily wiped out by some sort of plague or somesuch. The only possible conclusion is that we have to increase the "productivity" of the strong and decrease that of the weak. In practice, this has meant killing the weak, forcibly sterilising them, discouraging them from getting married, peddling contraception and abortion to them, and least distasteful of all, encouraging the "strong" to have more children. There are many fallacies bound in this view, and I want to go through a few of them because some are not so obvious.
Fallacy number 1: we're getting weaker.
Genetically speaking, this is perhaps true, in some ways. That's one of the things that makes it such a tempting thing to think about. The theory of evolution tells us that if you decrease selection pressure on a population then you will, on average, see those individuals that would not have been able to survive previously survive and have offspring. In our modern caring society many people who in the stone age would have died because of medical conditions no longer have their heads explode and thus pass on those defective genes to the next generation, making their condition more likely in the future.
Have you spotted the fallacy yet? Here it is: we have become weaker because fewer people are dying. Um, what? From an evolutionary standpoint, fewer members of a species dying means that they are stronger, better adapted, fitter. Modern society and technology gives us more machines meaning less toil, better medicine meaning when we get sick we have a good chance of getting better, more wealth meaning we have more varied and interesting lives. This is not called "things getting worse", so the idea that we are worse off with all these genetic degenerates is absolute crap.
Fallacy number 2: getting rid of the weak would make us stronger.
The idea here is that we should stop the weak having babies and make the strong have lots more babies to make up the shortfall. The result would be a stronger population overall and if calamity hit then we'd be better placed to weather it.
This fallacy is harder to spot, but have you seen it yet? Here it is: decreasing our genetic diversity would make us stronger. Um, what? Statistically speaking, a large population is fitter than a small one because it has more genetic variation, so even if we were subjected to a terrible catastrophe where a large fraction of the people died, the fact that there are more of us with more variability makes us more resilient, not less.
Fallacy number 3: some people have no significant value to society.
This one is true, actually - of the eugenicists, mostly, at least in their capacity as proponents of eugenics. The idea here is that people with severe genetic handicaps are totally pointless. There's no benefit to having them live - in fact, they are a nett drain on society's precious, finite resources. We'd be much better off screening against such people before birth and investing our resources in babies with sound physical and mental abilities. This particular view is fairly common nowadays - even though when you subject it to the light of truth it is monstrous - and it results in many abortions every year.
Spotted the fallacy yet? Here it is: some people are worth more dead than alive. Um, what? This comes out of a completely skewed view of the value of human life - specifically, that it is measured in economic terms. Practically this would mean that you need to earn your right to live, which means that if someone murdered you before you'd done that, it would be perfectly OK. It means that life is not a right, but a privilege which can be revoked by others. It means that you do not own your body, it is owned by others - perhaps medical experts. Since the right to life, or ownership of oneself, is the most fundamental principle of civilisation, this perspective can only make us worse-off (to put it mildly). The fact that this is a common justification for abortion shows how misguided some have become. Even if you consider abortion totally ordinary and not at all a bad thing, the view that results in abortions of babies who are deemed to be not worth raising is monstrous.
I hope that I have shown that the major beliefs of eugenics are simply ideological and have no basis in real improvements in society. They therefore have no place in society and I reserve the utmost rejection of these views and I will ostracise anyone coming to me with them severely. If we really want to improve society, we can do little better than provide the most freedom and private property that can be physically possible. That is what has made us the powerful society we are today and we seem to have largely forgotten it. Beware of anyone who says that some other person's life is not worthwhile. He is attacking the foundation of civilisation itself, and that is no understatement.
Fallacy number 1: we're getting weaker.
Genetically speaking, this is perhaps true, in some ways. That's one of the things that makes it such a tempting thing to think about. The theory of evolution tells us that if you decrease selection pressure on a population then you will, on average, see those individuals that would not have been able to survive previously survive and have offspring. In our modern caring society many people who in the stone age would have died because of medical conditions no longer have their heads explode and thus pass on those defective genes to the next generation, making their condition more likely in the future.
Have you spotted the fallacy yet? Here it is: we have become weaker because fewer people are dying. Um, what? From an evolutionary standpoint, fewer members of a species dying means that they are stronger, better adapted, fitter. Modern society and technology gives us more machines meaning less toil, better medicine meaning when we get sick we have a good chance of getting better, more wealth meaning we have more varied and interesting lives. This is not called "things getting worse", so the idea that we are worse off with all these genetic degenerates is absolute crap.
Fallacy number 2: getting rid of the weak would make us stronger.
The idea here is that we should stop the weak having babies and make the strong have lots more babies to make up the shortfall. The result would be a stronger population overall and if calamity hit then we'd be better placed to weather it.
This fallacy is harder to spot, but have you seen it yet? Here it is: decreasing our genetic diversity would make us stronger. Um, what? Statistically speaking, a large population is fitter than a small one because it has more genetic variation, so even if we were subjected to a terrible catastrophe where a large fraction of the people died, the fact that there are more of us with more variability makes us more resilient, not less.
Fallacy number 3: some people have no significant value to society.
This one is true, actually - of the eugenicists, mostly, at least in their capacity as proponents of eugenics. The idea here is that people with severe genetic handicaps are totally pointless. There's no benefit to having them live - in fact, they are a nett drain on society's precious, finite resources. We'd be much better off screening against such people before birth and investing our resources in babies with sound physical and mental abilities. This particular view is fairly common nowadays - even though when you subject it to the light of truth it is monstrous - and it results in many abortions every year.
Spotted the fallacy yet? Here it is: some people are worth more dead than alive. Um, what? This comes out of a completely skewed view of the value of human life - specifically, that it is measured in economic terms. Practically this would mean that you need to earn your right to live, which means that if someone murdered you before you'd done that, it would be perfectly OK. It means that life is not a right, but a privilege which can be revoked by others. It means that you do not own your body, it is owned by others - perhaps medical experts. Since the right to life, or ownership of oneself, is the most fundamental principle of civilisation, this perspective can only make us worse-off (to put it mildly). The fact that this is a common justification for abortion shows how misguided some have become. Even if you consider abortion totally ordinary and not at all a bad thing, the view that results in abortions of babies who are deemed to be not worth raising is monstrous.
I hope that I have shown that the major beliefs of eugenics are simply ideological and have no basis in real improvements in society. They therefore have no place in society and I reserve the utmost rejection of these views and I will ostracise anyone coming to me with them severely. If we really want to improve society, we can do little better than provide the most freedom and private property that can be physically possible. That is what has made us the powerful society we are today and we seem to have largely forgotten it. Beware of anyone who says that some other person's life is not worthwhile. He is attacking the foundation of civilisation itself, and that is no understatement.
Gold: some little-known factoids
Nowadays, very few people have any experience with large quantities of gold. This was mostly true in years past, of course, since there has never been and will never be a "lot" of gold around. However, this lack of understanding about the yellow metal does lead to some pretty interesting assumptions and depictions.
What started all this off was when I saw the new movie Tintin, yesterday. It was a pretty ordinary movie, as these things go, but apart from all that at the centre of the plot is some sort of gold treasure. This is described as "four hundredweight of gold" which is depicted in the film as a secret hold in a wooden ship about 1 foot deep in gold coin and assorted jewels and treasures. This brings my to my first factoid:
1. Gold is much denser than is generally supposed.
Most people's experience with the density of metals comes from steel. When we pick up an aluminium object, at least, when I do, I often get "tricked" by how light it is, especially if I can't see what colour the metal is. Iron and most steels hover around the 7.8 g/cc mark, meaning that a cubic meter of them would weigh 7.8 tonnes. Put another way, a tonne would occupy 128 L of volume, or a cube 50 cm on a side. Gold is considerably denser than iron, at more than 19 g/cc. A one tonne cube of gold, should you ever be unlucky enough to be asked to move one, would be just over 37 cm on a side. This means that the amount of gold depicted in the Tintin movie is something like 10 or 20 tonnes, way more than the 200 kg or so that "four hundredweight" would represent.
This also makes gold dangerous, specifically, the types of gold bars used to store gold in vaults. The bars in the Fort Knox depository each weigh about 12.5 kg and are only an 4.5 cm wide, so you can imagine crushing a finger by dropping one just a small distance. The heaviest bar ever made weighs 250 kg and if I remember correctly, if you can pick it up you can have it.

2. Gold is inert.
Most people do know this one, but it's actually pretty amazing just how reluctant gold is to do anything, chemically speaking. Not many metals could shrug off a bath of concentrated sulphuric acid or caesium hydroxide solution (dissolves glass, your dog etc), but gold can. That's all I can say without being boring about this one. This is one of the reasons we plate quite a lot of gold onto electrical connections. It doesn't help conductivity much per se but it does prevent corrosion forming that would affect the conductivity of the join.
3. Gold is soft.
Gold is by no means the softest metal around, but it is pretty limp for a metal that is often used to make objects out of. That's why in some movies about the old West you see people biting gold coins. If you bit into an iron coin plated with gold then it would not leave teeth marks but gold will flow even under this modest pressure. This also makes it lovely for making fine jewelery, since you don't need a hammer to make it do the intricate shapes.
4. Gold is malleable.
This might seem like the same thing as soft, but the two are only slightly related. Malleability is the tendency of a metal to remain soft as you work it. Copper, while quite soft is not very malleable. It will work harden into something impossibly unworkable, but gold will keep on flowing smoothly and evenly no matter how much you hammer it. This means you can hammer (or roll, these days) gold into incredibly thin sheets or wires.
5. Gold is an exceptional heat reflector.
6. Gold supports surface plasmons.
This is really esoteric for most people, but the practical upshot is that you can use gold to make red glass:
 This is also called cranberry glass, and its rather nice colour comes not from gold ions but very small particles of gold embedded in the glass. So if you divide this yellow metal up finely enough, it begins to appear red. Silver also does something similar but most glass colouring as a result of the presence of metals invove their ions, not nanoparticles, making this type of glass fairly unique.
What started all this off was when I saw the new movie Tintin, yesterday. It was a pretty ordinary movie, as these things go, but apart from all that at the centre of the plot is some sort of gold treasure. This is described as "four hundredweight of gold" which is depicted in the film as a secret hold in a wooden ship about 1 foot deep in gold coin and assorted jewels and treasures. This brings my to my first factoid:
1. Gold is much denser than is generally supposed.
Most people's experience with the density of metals comes from steel. When we pick up an aluminium object, at least, when I do, I often get "tricked" by how light it is, especially if I can't see what colour the metal is. Iron and most steels hover around the 7.8 g/cc mark, meaning that a cubic meter of them would weigh 7.8 tonnes. Put another way, a tonne would occupy 128 L of volume, or a cube 50 cm on a side. Gold is considerably denser than iron, at more than 19 g/cc. A one tonne cube of gold, should you ever be unlucky enough to be asked to move one, would be just over 37 cm on a side. This means that the amount of gold depicted in the Tintin movie is something like 10 or 20 tonnes, way more than the 200 kg or so that "four hundredweight" would represent.
This also makes gold dangerous, specifically, the types of gold bars used to store gold in vaults. The bars in the Fort Knox depository each weigh about 12.5 kg and are only an 4.5 cm wide, so you can imagine crushing a finger by dropping one just a small distance. The heaviest bar ever made weighs 250 kg and if I remember correctly, if you can pick it up you can have it.

You'd look pretty stupid with that for a hand, though
2. Gold is inert.
Most people do know this one, but it's actually pretty amazing just how reluctant gold is to do anything, chemically speaking. Not many metals could shrug off a bath of concentrated sulphuric acid or caesium hydroxide solution (dissolves glass, your dog etc), but gold can. That's all I can say without being boring about this one. This is one of the reasons we plate quite a lot of gold onto electrical connections. It doesn't help conductivity much per se but it does prevent corrosion forming that would affect the conductivity of the join.
3. Gold is soft.
Gold is by no means the softest metal around, but it is pretty limp for a metal that is often used to make objects out of. That's why in some movies about the old West you see people biting gold coins. If you bit into an iron coin plated with gold then it would not leave teeth marks but gold will flow even under this modest pressure. This also makes it lovely for making fine jewelery, since you don't need a hammer to make it do the intricate shapes.
4. Gold is malleable.
This might seem like the same thing as soft, but the two are only slightly related. Malleability is the tendency of a metal to remain soft as you work it. Copper, while quite soft is not very malleable. It will work harden into something impossibly unworkable, but gold will keep on flowing smoothly and evenly no matter how much you hammer it. This means you can hammer (or roll, these days) gold into incredibly thin sheets or wires.
5. Gold is an exceptional heat reflector.
Many times you will see gold foil in a satellite. The Lunar Module had quite a lot of gold foil on it as well, and the reason for this is that gold is the best way to stop heat radiation, or to reflect it, more precisely. This also means that it is used in some top end race cars and F1 cars around the engine bay, to prevent the heat generated by the engine from leaking out and damaging sensitive part of the car. Satellites are similarly protected from the intense heat radiation coming from the Sun.

Of course, not every satellite is made entirely of gold
6. Gold supports surface plasmons.
This is really esoteric for most people, but the practical upshot is that you can use gold to make red glass:
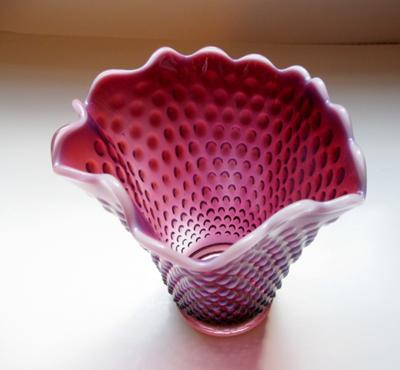 This is also called cranberry glass, and its rather nice colour comes not from gold ions but very small particles of gold embedded in the glass. So if you divide this yellow metal up finely enough, it begins to appear red. Silver also does something similar but most glass colouring as a result of the presence of metals invove their ions, not nanoparticles, making this type of glass fairly unique.
Tuesday, 27 December 2011
A new precious metal standard
A lot of economists of the Austrian or "philosophical" (as I like to call them) school yearn to be back on the gold standard. This, it seems, is the gold standard of money supply options. It solves all the problems of inflation, deflation government credit expansion and private credit expansion, so it must be good, right?

Well, sort of. Most of these people would, I imagine, envision a return to gold coins and private bank notes backed up by 100% reserve requirements. Personally I think that gold is too valuable and will make small transactions tricky. The obvious answer is silver but then you can't go bimetallic with a fixed exchange rate or there will be trouble. The other problem with gold and silver, the most serious problem as I see it, is that they are quite soft and suffer wear, thus lowering their value over time. There are engineering solutions to this, and I believe I have come up with one of them.
Most coins of the last few centuries are pretty similar. Raised images and lettering on both sides, with a raised edge produced through rolling. These days the raised edge is just part of the work hardening of the piece, really, since most coins contain a large amount of copper, but in the past it was there to make coin clipping easily visible. Coin clipping is the practice of cutting pieces off a precious metal coin in order to sell the valuable metal or strike your own coins. Precious metal coins are supposed to be a particular weight and purity, which is certified by the fact that they are struck as coins. Leave most of the coin intact while removing a small piece of it, and you can spend the coin at the same value as before, plus you now have some extra gold to sell.
The fact that a substantial portion of the coin is proud gives us the chance to produce a more durable gold or silver coin. Simply replace the edge and the images with some superalloy like inconel, strike the whole thing together and you have a (mostly) gold coin with that attractive two tone finish that can really handle the ravages of everyday commerce.

Gold is so much more valuable than inconel that it will represent nearly all of the coin's value, and you may then produce coins with quite a small amount of gold set into them to make smaller denominations. Speaking of which, here comes engineering solution number two.
 It is not enough to simply put vanishingly small amounts of gold into a coin. This would cause problems if nickel or any of the other major constituents of inconel were to seriously appreciate in value at some future date. You must therefore use a third, intermediate value metal. Silver fits the bill perfectly. Traditionally, it was necessary to use coins of pure silver or pure gold, to allow transactions to occur in either metal at universal equal value, with a floating exchange rate between the two to avoid the consequences of Gresham's law. I don't think that is necessary. Since by using a nickel alloy we are effectively already on a bimetallic standard with mixed coins, let's introduce the silver gradually down the value scale. Very high denomination coins would be nearly all gold, then as we go to lower denominations there would be an increasing fraction of silver until silver was the only "precious" metal in a particular denomination, and then we could increase the inconel content to get the lower denominations. This pretty much solves the exchange rate problem since we would balance the face value of the coins to be related to the historical average exchange rate (about 40:1, if you were wondering), and the gradual change over of the metals gives the exchange rate actually quite a wide variability without the relative value of denominations close to one another changing significantly. In fact my analysis shows that you can actually modify the exchange rate by a factor of 1.5 and commerce would be virtually unaffected, unless someone tries to get change in 5c pieces of a $1000 coin. Exchange rate problems could occur, in fact, if gold or silver changed significantly in value relative to the other and many people got the idea to exchange high gold for high silver content coins, or vice versa. In this case the face value would be off by enough to make the arbitrage worthwhile. But there is a very simple solution to this as well: float the exchange rate for exchanges of coins with large differences in the magnitude of their face value. It's not really that inconvenient, since such exchanges would be rare and trying to fix the face values for all time would increase the number of such exchanges, so floating that rate makes them unprofitable, unless someone were to have prior knowledge of a relative price spike in either metal which is pretty rare.
Now we come to the sticky subject of bank notes. Under the above monetary system, it would be most efficient to have each bank duly print its own notes or perhaps contract some excellent third party printer, which amounts to the same thing, but, crucially, the bank notes should have the same denomination as the precious metal currency they are standing in for. When someone presents a bank with one of its own notes, say a $5, it should give a $5 coin, or if both parties agree, $5 in other change at whatever floating exchange the two agree on. Banks should in general be willing to accept the notes of other banks, since they can then simply go to the bank in question and demand their specie for use as loans or reserves.
Loans and demand deposits are an interesting one. If all demand notes were to have a specified loan lifetime then the interest the bank earned loaning the money out could pay the storage fee. The note could then be redeemed at any time after the loan expiry but, critically, there would be an incentive to redeem the note as soon as it fell due, since banks could charge a storage fee or keep the money loaned out earning them nice interest for which the bearer could not demand a return. He would then want to redeem the note and perhaps loan the money out again at a better interest rate, save it in his own safe or just spend it. Banks could even redeem demand notes sooner than the due date, for a small fee of course.
All of that would mean that the total money supply might be about double the amount of the actual gold and silver. Now let's consider loans. In this economy, all bank loans would come out of savings in those banks of actual savers who have actually deposited the money there. They could not simply print more demand notes than there was metal, since other banks and people would certainly come to redeem them. They would, however, print loan notes. These would be interest bearing assets given to people who deposit money for a given time at a given interest rate. The loan's value, due date and interest rate would be on the loan note. If the depositor fell on hard times he could liquidate the note by selling it to a bank, or anyone really. The price paid for it would closely relate to all three essential features of a loan: interest, term and principal. These loan notes, then, would not circulate as currency but would be rapidly convertable, making them a kind of money. Their impact on the money supply would not be great, however. The borrower would be given demand notes or specie, what he preferred would make little difference to the bank. Large loans might require a fairly hefty amount of gold so it would be more convenient for someone borrowing money to build a power station, for instance, to get that money as demand notes, but in principle any form of money would be equal.

Gold
Well, sort of. Most of these people would, I imagine, envision a return to gold coins and private bank notes backed up by 100% reserve requirements. Personally I think that gold is too valuable and will make small transactions tricky. The obvious answer is silver but then you can't go bimetallic with a fixed exchange rate or there will be trouble. The other problem with gold and silver, the most serious problem as I see it, is that they are quite soft and suffer wear, thus lowering their value over time. There are engineering solutions to this, and I believe I have come up with one of them.
Most coins of the last few centuries are pretty similar. Raised images and lettering on both sides, with a raised edge produced through rolling. These days the raised edge is just part of the work hardening of the piece, really, since most coins contain a large amount of copper, but in the past it was there to make coin clipping easily visible. Coin clipping is the practice of cutting pieces off a precious metal coin in order to sell the valuable metal or strike your own coins. Precious metal coins are supposed to be a particular weight and purity, which is certified by the fact that they are struck as coins. Leave most of the coin intact while removing a small piece of it, and you can spend the coin at the same value as before, plus you now have some extra gold to sell.
The fact that a substantial portion of the coin is proud gives us the chance to produce a more durable gold or silver coin. Simply replace the edge and the images with some superalloy like inconel, strike the whole thing together and you have a (mostly) gold coin with that attractive two tone finish that can really handle the ravages of everyday commerce.

Not exactly what I meant but you get the idea
Gold is so much more valuable than inconel that it will represent nearly all of the coin's value, and you may then produce coins with quite a small amount of gold set into them to make smaller denominations. Speaking of which, here comes engineering solution number two.
 It is not enough to simply put vanishingly small amounts of gold into a coin. This would cause problems if nickel or any of the other major constituents of inconel were to seriously appreciate in value at some future date. You must therefore use a third, intermediate value metal. Silver fits the bill perfectly. Traditionally, it was necessary to use coins of pure silver or pure gold, to allow transactions to occur in either metal at universal equal value, with a floating exchange rate between the two to avoid the consequences of Gresham's law. I don't think that is necessary. Since by using a nickel alloy we are effectively already on a bimetallic standard with mixed coins, let's introduce the silver gradually down the value scale. Very high denomination coins would be nearly all gold, then as we go to lower denominations there would be an increasing fraction of silver until silver was the only "precious" metal in a particular denomination, and then we could increase the inconel content to get the lower denominations. This pretty much solves the exchange rate problem since we would balance the face value of the coins to be related to the historical average exchange rate (about 40:1, if you were wondering), and the gradual change over of the metals gives the exchange rate actually quite a wide variability without the relative value of denominations close to one another changing significantly. In fact my analysis shows that you can actually modify the exchange rate by a factor of 1.5 and commerce would be virtually unaffected, unless someone tries to get change in 5c pieces of a $1000 coin. Exchange rate problems could occur, in fact, if gold or silver changed significantly in value relative to the other and many people got the idea to exchange high gold for high silver content coins, or vice versa. In this case the face value would be off by enough to make the arbitrage worthwhile. But there is a very simple solution to this as well: float the exchange rate for exchanges of coins with large differences in the magnitude of their face value. It's not really that inconvenient, since such exchanges would be rare and trying to fix the face values for all time would increase the number of such exchanges, so floating that rate makes them unprofitable, unless someone were to have prior knowledge of a relative price spike in either metal which is pretty rare.
Now we come to the sticky subject of bank notes. Under the above monetary system, it would be most efficient to have each bank duly print its own notes or perhaps contract some excellent third party printer, which amounts to the same thing, but, crucially, the bank notes should have the same denomination as the precious metal currency they are standing in for. When someone presents a bank with one of its own notes, say a $5, it should give a $5 coin, or if both parties agree, $5 in other change at whatever floating exchange the two agree on. Banks should in general be willing to accept the notes of other banks, since they can then simply go to the bank in question and demand their specie for use as loans or reserves.
Loans and demand deposits are an interesting one. If all demand notes were to have a specified loan lifetime then the interest the bank earned loaning the money out could pay the storage fee. The note could then be redeemed at any time after the loan expiry but, critically, there would be an incentive to redeem the note as soon as it fell due, since banks could charge a storage fee or keep the money loaned out earning them nice interest for which the bearer could not demand a return. He would then want to redeem the note and perhaps loan the money out again at a better interest rate, save it in his own safe or just spend it. Banks could even redeem demand notes sooner than the due date, for a small fee of course.
All of that would mean that the total money supply might be about double the amount of the actual gold and silver. Now let's consider loans. In this economy, all bank loans would come out of savings in those banks of actual savers who have actually deposited the money there. They could not simply print more demand notes than there was metal, since other banks and people would certainly come to redeem them. They would, however, print loan notes. These would be interest bearing assets given to people who deposit money for a given time at a given interest rate. The loan's value, due date and interest rate would be on the loan note. If the depositor fell on hard times he could liquidate the note by selling it to a bank, or anyone really. The price paid for it would closely relate to all three essential features of a loan: interest, term and principal. These loan notes, then, would not circulate as currency but would be rapidly convertable, making them a kind of money. Their impact on the money supply would not be great, however. The borrower would be given demand notes or specie, what he preferred would make little difference to the bank. Large loans might require a fairly hefty amount of gold so it would be more convenient for someone borrowing money to build a power station, for instance, to get that money as demand notes, but in principle any form of money would be equal.
Monday, 26 December 2011
Hyperinflation 2
In my previous treatment of hyperinflation I said that instead of thinking of it as a monetary phenominon, happening when a government prints a lot of currency very fast, we should think of it as a systemic rejection of the currency by everyone engaging in commerce. At that time I didn't have proof, but now with money supply figures I got out of Wikipedia, I think I can demonstrate the point.
OK the way this is done is, we take the value of the Zimbabwe dollar in terms of US dollars and multiply it by the number of Zimbabwe dollars we think might have been around at every particular time and, voila, that gives us the value of the money supply. Now, it is important to realise that all of the figures I used are subject to systemic and random error, and there are large gaps I had to fill in with numbers I guessed were intermediate. So you can forget about accuracy, but I do believe that the data will still serve to illustrate my point.
The first chart shows the relative value of the Zimbabwe dollar over 10 months of the hyperinflation. As you will see, holding on to the currency at this time is economic suicide. Your money will be essentially worthless in about half a year:
 This period, beginning on 5th of January 2007, doesn't even deal with the worst hyperinflation. Under extreme hyperinflation the graph has roughly the same shape, but the time taken to lose all your money can be measured in days or even hours.
In order to chart the magnitude of inflations this high, we have to resort to logarithmic measurements. The chart below shows the growth in the amount of money you would have to give in exchange for US currency:
 0 here means 1, which is the index point on 5th of January 2007. Two and a half years later you'd need $853 sextillion to buy the same thing. Such numbers are simply beyond the experience of everyone. Even physicists who regularly deal with extremely small numbers (like the size of an atom) or very large ones (like the mass of the galaxy) would have trouble getting their heads around this one. Rather conveniently, for me, it is roughly the number of atoms in a lump of aluminium weighing 38 grams. If you laid those atoms end to end in a single line, they would go from the Sun to Neptune and back 12 times. See what I mean?
Now that we have some idea of the changing value of the currency, we need to have some idea of the amount of currency in circulation. The chart below shows a very rough view of the money supply - on a logarythmic scale, of course, otherwise the fine structure of the graph would disappear and we'd just have a "hockey stick":
 This chart begins in August 2006. These figures are subject to a lot of uncertainty, of course, but as a ball park this allows us to get some idea of the value of the money supply:
 Bingo! Observe the money supply's value going to 0. Again, this tracks the supply from 5th of January 2007. An important point on this data is that the first 11 months is a period when the Reserve bank did not report money supply data, so it is pure interpolation. There is further interpolation later on as well, but the overall picture is not deceptive: the money supply is being rejected and the most interesting portion of the graph, around 10-14 months, has plenty of data points. Consider the logarithmic version of this chart:
 The bubble towards the end there is telling us that the very large increase in the money supply that happened around the beginning of 2008 temporarily caused an uptake in the economy. People started to accept the new currency, but notice how quickly that currency bubble went south. Five months later, the currency was worse off than ever, even though the face value was rocketing upward. At this point the currency was re-indexed at a rate of 10 billion old dollars is 1 new dollar. The fresh currency has been no better accepted.
OK the way this is done is, we take the value of the Zimbabwe dollar in terms of US dollars and multiply it by the number of Zimbabwe dollars we think might have been around at every particular time and, voila, that gives us the value of the money supply. Now, it is important to realise that all of the figures I used are subject to systemic and random error, and there are large gaps I had to fill in with numbers I guessed were intermediate. So you can forget about accuracy, but I do believe that the data will still serve to illustrate my point.
The first chart shows the relative value of the Zimbabwe dollar over 10 months of the hyperinflation. As you will see, holding on to the currency at this time is economic suicide. Your money will be essentially worthless in about half a year:
 This period, beginning on 5th of January 2007, doesn't even deal with the worst hyperinflation. Under extreme hyperinflation the graph has roughly the same shape, but the time taken to lose all your money can be measured in days or even hours.
In order to chart the magnitude of inflations this high, we have to resort to logarithmic measurements. The chart below shows the growth in the amount of money you would have to give in exchange for US currency:
 0 here means 1, which is the index point on 5th of January 2007. Two and a half years later you'd need $853 sextillion to buy the same thing. Such numbers are simply beyond the experience of everyone. Even physicists who regularly deal with extremely small numbers (like the size of an atom) or very large ones (like the mass of the galaxy) would have trouble getting their heads around this one. Rather conveniently, for me, it is roughly the number of atoms in a lump of aluminium weighing 38 grams. If you laid those atoms end to end in a single line, they would go from the Sun to Neptune and back 12 times. See what I mean?
Now that we have some idea of the changing value of the currency, we need to have some idea of the amount of currency in circulation. The chart below shows a very rough view of the money supply - on a logarythmic scale, of course, otherwise the fine structure of the graph would disappear and we'd just have a "hockey stick":
 This chart begins in August 2006. These figures are subject to a lot of uncertainty, of course, but as a ball park this allows us to get some idea of the value of the money supply:
 Bingo! Observe the money supply's value going to 0. Again, this tracks the supply from 5th of January 2007. An important point on this data is that the first 11 months is a period when the Reserve bank did not report money supply data, so it is pure interpolation. There is further interpolation later on as well, but the overall picture is not deceptive: the money supply is being rejected and the most interesting portion of the graph, around 10-14 months, has plenty of data points. Consider the logarithmic version of this chart:
 The bubble towards the end there is telling us that the very large increase in the money supply that happened around the beginning of 2008 temporarily caused an uptake in the economy. People started to accept the new currency, but notice how quickly that currency bubble went south. Five months later, the currency was worse off than ever, even though the face value was rocketing upward. At this point the currency was re-indexed at a rate of 10 billion old dollars is 1 new dollar. The fresh currency has been no better accepted.
Subscribe to:
Posts (Atom)